The Federal Reserve is set to hold rates this week: Why a December hike is virtually fully priced anyway
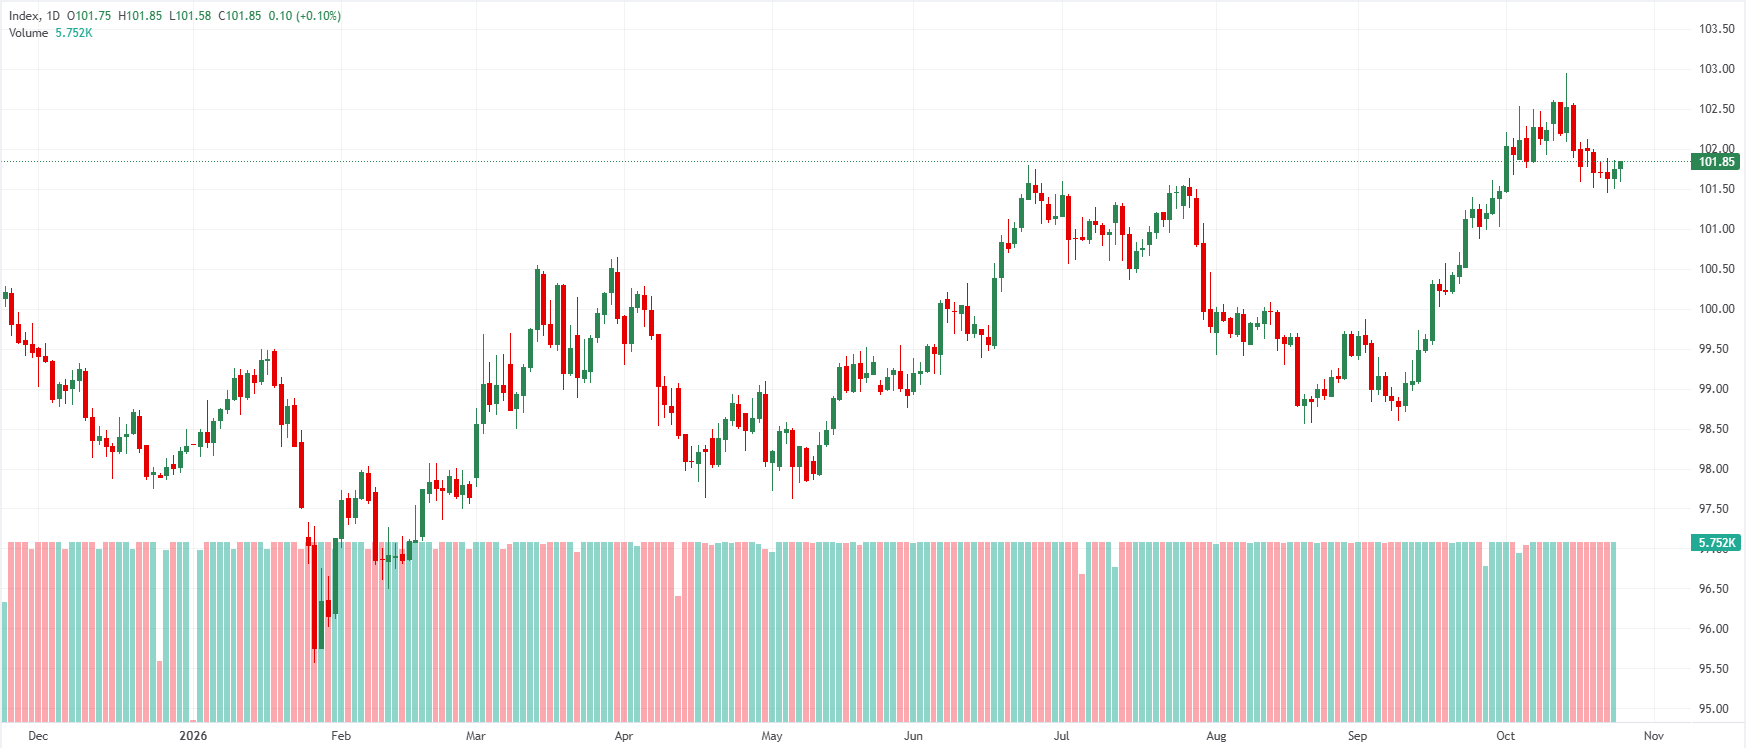
The US Dollar (USD) maintains a well-supported stance across global FX markets as traders anticipate the Federal Reserve will keep the Fed funds rate steady at 3.75–4.00% at its upcoming policy meeting on Wednesday. With futures markets pricing in just 10% odds of an October rate increase, investors’ focus has rapidly shifted to the underlying resilience of US economic growth and persistent price pressures. Driven by projections of strong Q3 real GDP expansion near 3.2% annualized and accelerating core PCE inflation, institutional strategists at Brown Brothers Harriman (BBH) and TD Securities view the expected policy pause not as a dovish pivot, but as a tactical prelude to further monetary tightening in December that will preserve the Greenback's yield advantage.
BBH sees Fed pause underpinning the ongoing US Dollar strength
Elias Haddad at Brown Brothers Harriman (BBH) expects the Federal Reserve to leave interest rates unchanged at 3.75–4.00% this week, noting that calls for patience among key Fed officials match market pricing of just 10% odds for an October hike. However, with Q3 GDP projected to expand at a 3.2% annualized pace and September core PCE accelerating to 3.1% yearly, Haddad argues that booming private sector activity and persistent inflation risks will keep the US Dollar firmly supported while a December rate hike is virtually fully priced in.
"The FOMC is expected to keep the Fed funds target range steady at 3.75-4.00% after raising rates 25bps in September. Calls for patience from several key Fed officials support a pause. Futures market imply only 10% odds of a hike this week, with a December 9 rate increase virtually fully price in... Overall, robust US economic activity and rising price pressures argue for additional Fed funds rate hikes, offering ongoing USD support... Headline PCE is seen rising 0.5% m/m... and quicken to 3.6% y/y... Real GDP growth is anticipated to rise 3.2% annualized... driven by consumer spending and AI-related business investment."
TD Securities expects October hold to pave way for December rate hike
Oscar Munoz and Eli Nir at TD Securities project that the Fed will maintain its policy rate at 3.75-4.00% in October, validating current market expectations while refraining from aggressive new forward guidance. They emphasize that pausing in October actually raises the probability of a rate hike in December, with potential for a larger 50 basis points (bps) move if inflation data stay firm. TD Securities maintains a hawkish cycle outlook, expecting two further rate increases in December and March to combat sticky price pressures.
"We expect the FOMC to keep rates on hold this week despite rising inflation risks. The chance of a surprise hike is higher than normal, but we believe they will prioritize patience and wait until December. A hold in October will make a December hike all the more likely. After the upside surprise in September CPI, inflation risks are still pertinent... We expect the Fed to hike two more times (December and March). Inflation remains above target while risks are growing."
Key Takeaway
The widely expected FOMC decision to hold rates at 3.75–4.00% reflects tactical patience rather than a dovish turn, maintaining a highly supportive backdrop for the US Dollar. While BBH points to accelerating PCE inflation (3.6% year-on-year) and robust Q3 GDP growth (3.2% annualized) driven by AI investment as key drivers keeping the Greenback well-bid, TD Securities emphasizes that an October pause elevates the likelihood of subsequent tightening in December and March, ensuring that the US Dollar's interest rate advantage remains firmly intact into the coming year.
(This article was created with the help of an Artificial Intelligence tool and reviewed by an editor. Know more.)
Author

FXStreet Insights Team
FXStreet
The FXStreet Insights Team is a group of journalists that handpicks selected market observations published by renowned experts. The content includes notes by commercial as well as additional insights by internal and external analysts.

















