The British Pound goes into retail sales with its November hike already priced
- GBP/USD sits still under 1.3400 as UK inflation rises to 3.5%, the highest this year.
- Odds of a second BoE hike by December fall to about 48% from 58%.
- UK retail sales on Friday are forecast to fall 0.1% after a 0.5% rise.
UK inflation beat its forecast on the headline, core and monthly measures on Wednesday, and the Pound barely moved. GBP/USD holds just under 1.3400, with no daily close above it since September 15. Traders had a Bank of England (BoE) hike for November 5 almost fully priced before the release, so the number could only change how much of that hike was left to buy.
Hot inflation added three points to a hike priced at 93%
Consumer Price Index (CPI) inflation rose to 3.5% in September from 3.1%, against a 3.4% forecast, and the core rate rose to 2.8% from 2.6%. Prices rose 0.4% on the month against a 0.3% forecast. Transport made the largest upward contribution, with diesel at its dearest since July 2022 and Brent near $109.00 a barrel on the US-Iran war. Producer output prices rose 0.8% on the month, a tenth above forecast, so the costs feeding the next few months of shop prices are still climbing.
Traders put the chance that the BoE raises the UK's Bank Rate from 3.75% on November 5 at about 96% after the release, up from about 93% before it. The Pound gets a hike's lift when traders price it, and this one was already 93% priced. The same release cut the odds of a second hike by December to about 48% from 58%, so a hotter inflation report left the market expecting fewer UK hikes this year, not more.
Services inflation rose in the first report since Governor Bailey called the spillover limited
BoE Governor Bailey said on October 16 that he saw little evidence yet of the energy shock feeding into pay and the prices of everything else, which is what economists call second-round effects. Services inflation, the figure the BoE watches most closely for that, rose to 3.7% from 3.4% in Wednesday's report, and recreation and culture prices rose to 2.3% from 1.6%.
A spillover into services is what turns one hike into several, and several hikes are the part of the BoE story not yet in the Pound's price. October's inflation figures come out after the November 5 decision, which makes Wednesday's report the last one the Monetary Policy Committee (MPC) sees before it votes.
The Office for National Statistics (ONS) also put public sector net borrowing at £24.52 billion for September, with spending, debt interest included, rising faster than income. That bill goes into Chancellor Healey's first Budget on October 28. The 10-year gilt yield ended September just below 5.4% after a 19-year high earlier in the month, so a Budget that borrows more could reach the Pound through the bond market before the BoE votes.
The Budget lands on Fed day, a week before the BoE votes
GfK consumer confidence at 23:01 GMT on Thursday is forecast at -15 after -13. Retail sales follow at 06:00 GMT on Friday, forecast to fall 0.1% on the month after a 0.5% rise, with annual growth slowing to 1% from 2.4%. Sales excluding fuel are forecast to grow 1.5% on the year, faster than the total, so the forecasts have Britons buying less fuel than a year ago at the highest diesel prices since 2022.
S&P Global's preliminary UK Purchasing Managers Index (PMI) figures at 08:30 GMT on Friday are forecast at 51.8 for both manufacturing and services. The US versions at 13:45 GMT are forecast at 55.6 and 57.9, and University of Michigan sentiment at 14:00 GMT at 46.3, unchanged. A weak set of UK figures would hit the December odds first, since November is already in the price.
Chancellor Healey presents the Budget on October 28, the same day the Fed decides, with prediction markets near 86% for a hold at 3.75%-4.00%. The BoE follows on November 5 with a November hike already in the Pound's price and the December call still open.
The Pound's levels around its 200-day average
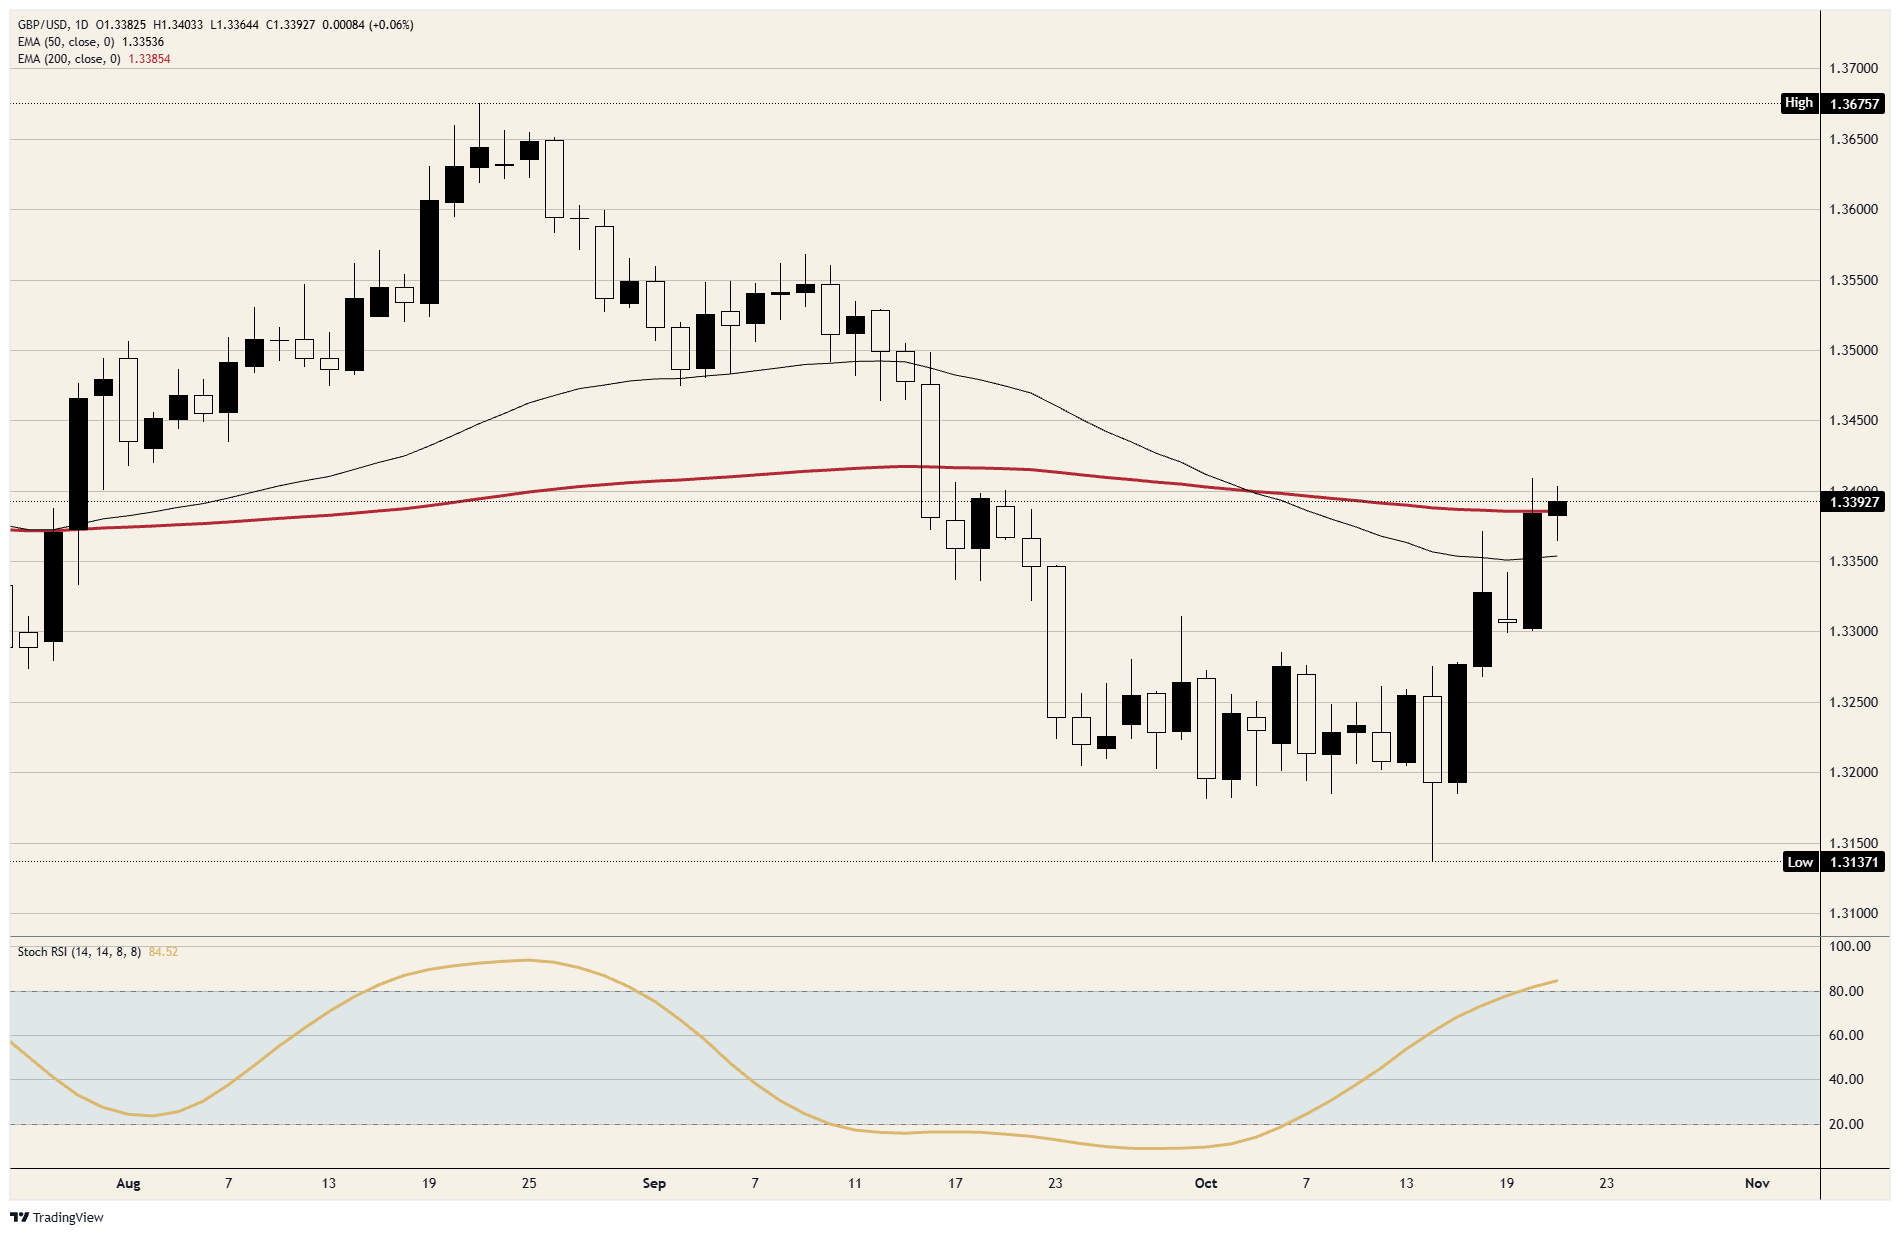
Resistance: 1.3400 stopped the highs on Tuesday and Wednesday, and GBP/USD hasn't had a daily close above it since September 15. 1.3500 is where the September 16 drop began.
Support: The 200-day Exponential Moving Average (EMA), just under 1.3400, is right under the price, and Tuesday was the first time the pair traded above it since mid-September. Wednesday's low just above 1.3350 comes next, then 1.3300, where Monday's dip ended.
Bias: Short below 1.3400 on a closing basis, looking for 1.3350 and then 1.3300. The daily Stochastic Relative Strength Index (Stoch RSI) has moved into overbought territory, near 85, after the climb from the October 14 low. A daily close above 1.3450 ends the short.
GBP/USD daily chart
Pound Sterling FAQs
The Pound Sterling (GBP) is the oldest currency in the world (886 AD) and the official currency of the United Kingdom. It is the fourth most traded unit for foreign exchange (FX) in the world, accounting for 12% of all transactions, averaging $630 billion a day, according to 2022 data. Its key trading pairs are GBP/USD, also known as ‘Cable’, which accounts for 11% of FX, GBP/JPY, or the ‘Dragon’ as it is known by traders (3%), and EUR/GBP (2%). The Pound Sterling is issued by the Bank of England (BoE).
The single most important factor influencing the value of the Pound Sterling is monetary policy decided by the Bank of England. The BoE bases its decisions on whether it has achieved its primary goal of “price stability” – a steady inflation rate of around 2%. Its primary tool for achieving this is the adjustment of interest rates. When inflation is too high, the BoE will try to rein it in by raising interest rates, making it more expensive for people and businesses to access credit. This is generally positive for GBP, as higher interest rates make the UK a more attractive place for global investors to park their money. When inflation falls too low it is a sign economic growth is slowing. In this scenario, the BoE will consider lowering interest rates to cheapen credit so businesses will borrow more to invest in growth-generating projects.
Data releases gauge the health of the economy and can impact the value of the Pound Sterling. Indicators such as GDP, Manufacturing and Services PMIs, and employment can all influence the direction of the GBP. A strong economy is good for Sterling. Not only does it attract more foreign investment but it may encourage the BoE to put up interest rates, which will directly strengthen GBP. Otherwise, if economic data is weak, the Pound Sterling is likely to fall.
Another significant data release for the Pound Sterling is the Trade Balance. This indicator measures the difference between what a country earns from its exports and what it spends on imports over a given period. If a country produces highly sought-after exports, its currency will benefit purely from the extra demand created from foreign buyers seeking to purchase these goods. Therefore, a positive net Trade Balance strengthens a currency and vice versa for a negative balance.
Author

Joshua Gibson
FXStreet
Joshua joins the FXStreet team as an Economics and Finance double major from Vancouver Island University with twelve years' experience as an independent trader focusing on technical analysis.
















