Gold slides as Trump comments cloud hopes for a Middle East peace deal
- Gold slides as fading hopes for a Middle East peace deal lift the US Dollar.
- The DXY rebounds after Trump warns the US will respond to an Iranian attack.
- Technically, bearish momentum remains in place as XAU/USD struggles below the Bollinger midline near $4,500.
Gold (XAU/USD) extends its decline to the lowest level since March on Tuesday as the US Dollar (USD) rebounds amid uncertainty surrounding a possible end to the war in the Middle East, while a hawkish Federal Reserve (Fed) outlook continues to weigh on the non-yielding metal.
At the time of writing, XAU/USD is trading around $4,260, down 1.60% on the day after retreating from an intraday high near $4,350.
US President Donald Trump said in a Truth Social post that Iran had shot down a US Apache helicopter patrolling over the Strait of Hormuz. Trump said both pilots were safe and uninjured, but added that the United States would need to respond to the attack.
Earlier on Tuesday, Trump said negotiations with Iran are in the "final throes" and that an agreement could be reached within days. "We're in the final throes of what will be a very, very good deal," Trump told reporters on Tuesday. He added that the Strait of Hormuz would reopen as soon as a deal is finalized.
The conflicting headlines dented hopes for a near-term peace deal, helping the US Dollar recover from earlier losses. The US Dollar Index (DXY), which tracks the Greenback's value against a basket of six major currencies, is trading around 100.00, rebounding from an intraday low of 99.68.
The next hurdle for Gold: US inflation
Traders are bracing for the US Consumer Price Index (CPI) report due on Wednesday.
Inflation has drifted further away from the central bank's 2% target, as higher Crude Oil prices following the outbreak of the war in the Middle East in late February have added to inflationary pressure. Annual CPI rose to 3.3% in March and 3.8% in April, with economists expecting a further increase to 4.2% in May.
A stronger-than-expected reading would cement bets on a rate hike later this year and increase pressure on Gold, which tends to perform well in a low-interest rate environment. In contrast, a softer inflation reading could allow the Fed to remain patient and trigger a short-term rebound in the precious metal.
Still, gains may be capped as markets remain convinced that interest rates will stay elevated for longer, unless a US-Iran agreement leads to a sustained decline in Oil prices and eases inflation concerns.
Technical analysis: XAU/USD stabilizes, but the technical picture remains fragile
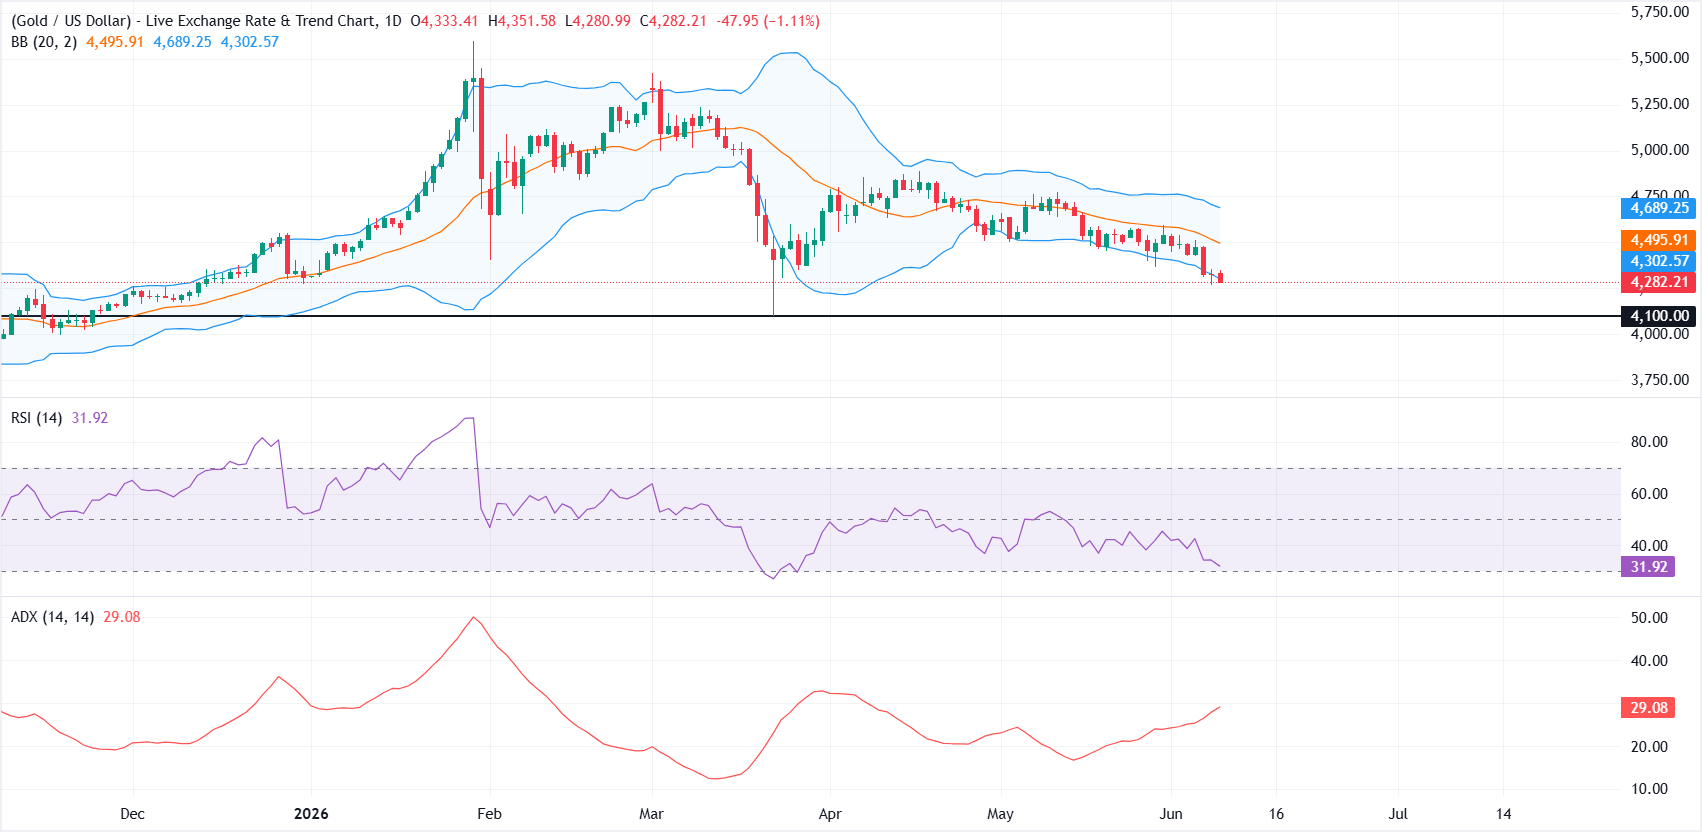
On the daily chart, XAU/USD holds below the Bollinger Bands’ 20-period Simple Moving Average near $4,496 and slips beneath the lower band around $4,306, keeping the near-term tone bearish. The Relative Strength Index (RSI) hovers in the low 30s, hinting at persistent but not yet extreme downside pressure, while the Average Directional Index (ADX) near 29 points to a strengthening trend backdrop rather than range-bound trade.
On the topside, initial resistance emerges at the lower Bollinger Band near $4,306, with the 20-period SMA around $4,497 acting as a more meaningful cap, ahead of the upper band close to $4,687. On the downside, the next noteworthy cushion sits at the horizontal support line near $4,100, where a break would open the door to a deeper corrective leg within the broader bearish configuration.
(The technical analysis of this story was written with the help of an AI tool.)
Inflation FAQs
Inflation measures the rise in the price of a representative basket of goods and services. Headline inflation is usually expressed as a percentage change on a month-on-month (MoM) and year-on-year (YoY) basis. Core inflation excludes more volatile elements such as food and fuel which can fluctuate because of geopolitical and seasonal factors. Core inflation is the figure economists focus on and is the level targeted by central banks, which are mandated to keep inflation at a manageable level, usually around 2%.
The Consumer Price Index (CPI) measures the change in prices of a basket of goods and services over a period of time. It is usually expressed as a percentage change on a month-on-month (MoM) and year-on-year (YoY) basis. Core CPI is the figure targeted by central banks as it excludes volatile food and fuel inputs. When Core CPI rises above 2% it usually results in higher interest rates and vice versa when it falls below 2%. Since higher interest rates are positive for a currency, higher inflation usually results in a stronger currency. The opposite is true when inflation falls.
Although it may seem counter-intuitive, high inflation in a country pushes up the value of its currency and vice versa for lower inflation. This is because the central bank will normally raise interest rates to combat the higher inflation, which attract more global capital inflows from investors looking for a lucrative place to park their money.
Formerly, Gold was the asset investors turned to in times of high inflation because it preserved its value, and whilst investors will often still buy Gold for its safe-haven properties in times of extreme market turmoil, this is not the case most of the time. This is because when inflation is high, central banks will put up interest rates to combat it. Higher interest rates are negative for Gold because they increase the opportunity-cost of holding Gold vis-a-vis an interest-bearing asset or placing the money in a cash deposit account. On the flipside, lower inflation tends to be positive for Gold as it brings interest rates down, making the bright metal a more viable investment alternative.
Author

Vishal Chaturvedi
FXStreet
I am a macro-focused research analyst with over four years of experience covering forex and commodities market. I enjoy breaking down complex economic trends and turning them into clear, actionable insights that help traders stay ahead of the curve.

















