GBP/JPY Price Forecast: Consolidates as intervention woes cap upside
- GBP/JPY consolidates below 215.61 as intervention risk caps upside.
- RSI favors upside, but shifting slope signals trader indecision.
- Break below SMA confluence exposes 214.00 and 212.93 support.
The Pound Sterling ended Thursday’s session almost flat at around 214.70 as market sentiment fluctuated but ultimately improved after US President Donald Trump cancelled attacks and hinted at a possible deal in place. The GBP/JPY traded with gains of almost 0.04%.
GBP/JPY Price Forecast: Technical outlook
Price action suggests the cross-pair is consolidating as traders refrain from pushing GBP/JPY higher amid fears of a possible Japanese authorities' intervention in USD/JPY. If they decided that the Yen is weaker and intervene, this would generate ripples, as the Japanese currency would appreciate against most G8 currencies.
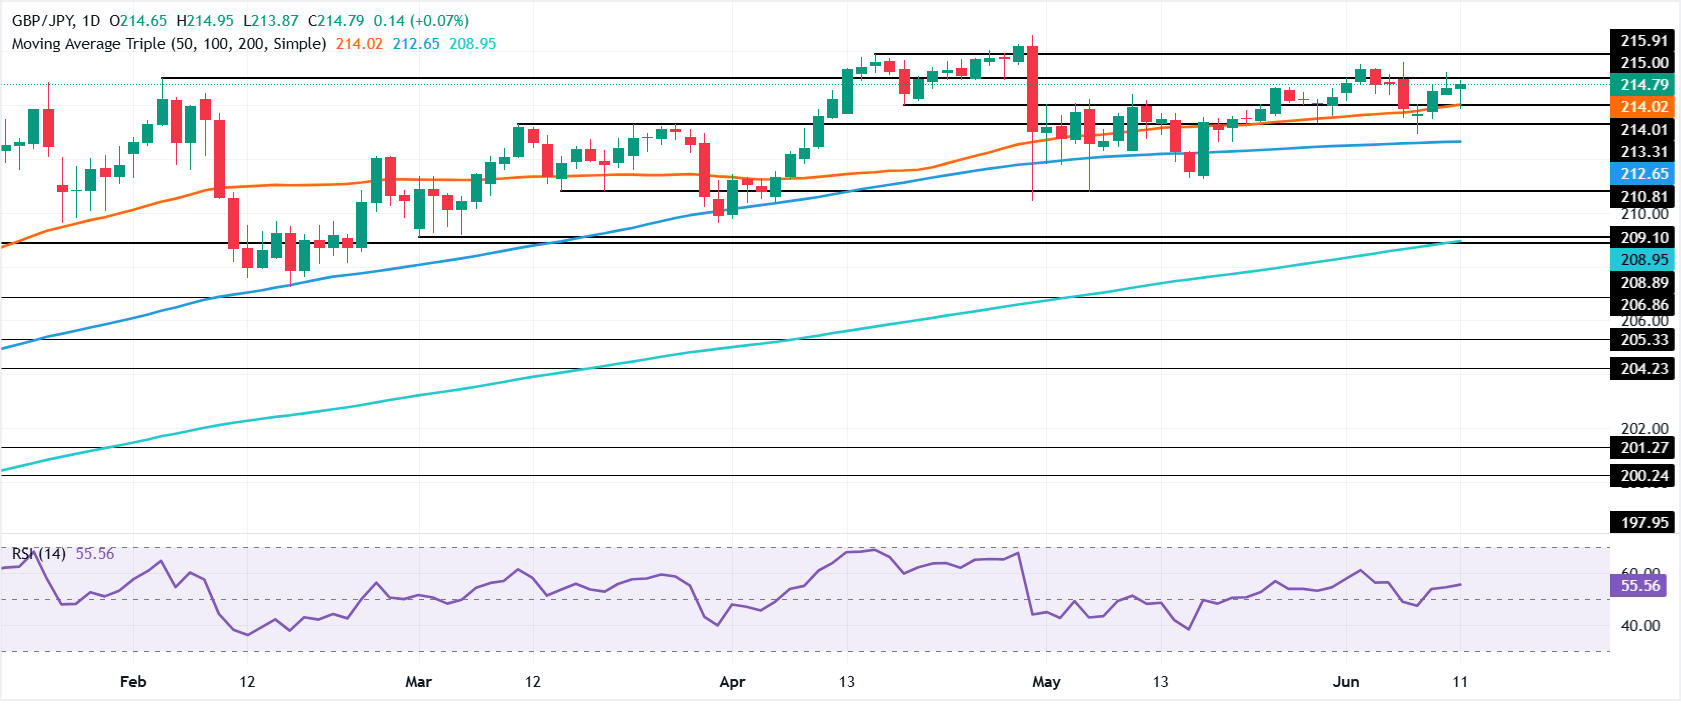
Hence, the GBP/JPY drifts higher, though steadily, but it remains unable to clear the most recent cycle high reached on June 5 at 215.61. Momentum, as measured by the Relative Strength Index (RSI), favours further upside, though it has shifted slightly, suggesting indecision.
If GBP/JPY surpasses the June 10 high at 215.24, the next stop would be the June 5 high at 215.61, followed by the year-to-date (YTD) high of 216.60.
On the flip side, if GBP/JPY drops below the confluence of the 20- and 50-day Simple Moving Averages (SMAs) at around the 214.23-214.10 area, this opens the door toward 214.00. Below this level sits the June 8 swing low of 212.93, ahead of the 100-day SMA at 212.67.
GBP/JPY Price Chart – Daily
Japanese Yen FAQs
The Japanese Yen (JPY) is one of the world’s most traded currencies. Its value is broadly determined by the performance of the Japanese economy, but more specifically by the Bank of Japan’s policy, the differential between Japanese and US bond yields, or risk sentiment among traders, among other factors.
One of the Bank of Japan’s mandates is currency control, so its moves are key for the Yen. The BoJ has directly intervened in currency markets sometimes, generally to lower the value of the Yen, although it refrains from doing it often due to political concerns of its main trading partners. The BoJ ultra-loose monetary policy between 2013 and 2024 caused the Yen to depreciate against its main currency peers due to an increasing policy divergence between the Bank of Japan and other main central banks. More recently, the gradually unwinding of this ultra-loose policy has given some support to the Yen.
Over the last decade, the BoJ’s stance of sticking to ultra-loose monetary policy has led to a widening policy divergence with other central banks, particularly with the US Federal Reserve. This supported a widening of the differential between the 10-year US and Japanese bonds, which favored the US Dollar against the Japanese Yen. The BoJ decision in 2024 to gradually abandon the ultra-loose policy, coupled with interest-rate cuts in other major central banks, is narrowing this differential.
The Japanese Yen is often seen as a safe-haven investment. This means that in times of market stress, investors are more likely to put their money in the Japanese currency due to its supposed reliability and stability. Turbulent times are likely to strengthen the Yen’s value against other currencies seen as more risky to invest in.
Author

Christian Borjon Valencia
FXStreet
Markets analyst, news editor, and trading instructor with over 14 years of experience across FX, commodities, US equity indices, and global macro markets.

















