GBP/JPY holds steady as traders eye BoE and BoJ rate decisions
- GBP/JPY range-bound near 212.00 as markets await BoE and BoJ monetary policy decisions.
- UK-Japan interest rate differential continues to support an upside bias in the cross.
- Technically, GBP/JPY holds above key moving averages, with a bearish flag in play but near-term momentum remaining positive.
The British Pound (GBP) trades broadly flat against the Japanese Yen (JPY) on Tuesday as a thin economic calendar keeps price action subdued, with attention firmly shifting to the Bank of England (BoE) and Bank of Japan (BoJ) interest rate decisions due on Thursday. At the time of writing, GBP/JPY trades around 212.15, holding close to the previous day’s high.
On the macro front, the wide interest rate differential between the UK and Japan continues to support an upside bias in GBP/JPY. The recent surge in Oil prices, driven by disruptions in the Strait of Hormuz amid the US–Iran war, is reinforcing inflation concerns and prompting a hawkish repricing of BoE rate expectations, providing additional support to the cross.
However, the BoJ faces a challenging backdrop, as persistent inflation may support further policy tightening, while higher energy costs could weigh on Japan’s economic growth, given its status as a major energy importer, clouding the outlook.
Nevertheless, both central banks are widely expected to keep rates unchanged at their upcoming meetings, with markets likely to focus on forward guidance for clues on how policymakers assess the economic impact of rising Oil prices.
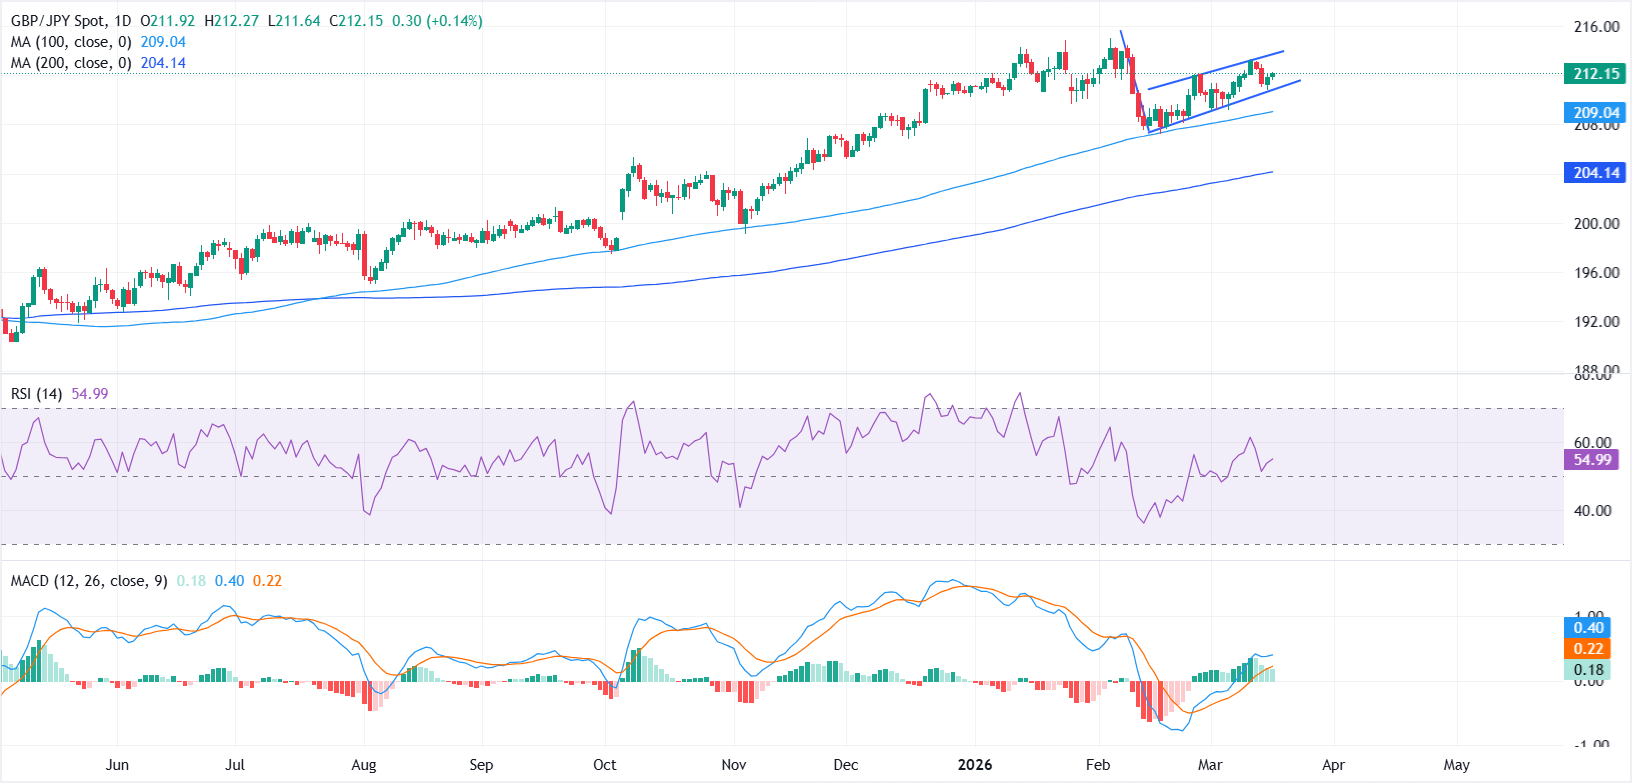
From a technical perspective, GBP/JPY appears to be forming a bearish flag pattern on the daily chart. However, the near-term bias remains tilted to the upside as the pair holds comfortably above the rising 100- and 200-day Simple Moving Averages (SMAs)
The Relative Strength Index (RSI) at 54 stays above its midline, suggesting moderate bullish momentum. The Moving Average Convergence Divergence (MACD) line remains above the Signal line in positive territory, with a still-positive histogram that supports persistent, if measured, buying pressure.
On the downside, a clear break below the lower boundary of the flag near the 211.00-210.50 region could expose the 100-day SMA around 209.00, followed by the 200-day SMA near 204.14. On the upside, initial resistance is seen near 213.00, close to the upper boundary of the flag, with a sustained break opening the door toward the 215.00 area, the February 4 high.
Central banks FAQs
Central Banks have a key mandate which is making sure that there is price stability in a country or region. Economies are constantly facing inflation or deflation when prices for certain goods and services are fluctuating. Constant rising prices for the same goods means inflation, constant lowered prices for the same goods means deflation. It is the task of the central bank to keep the demand in line by tweaking its policy rate. For the biggest central banks like the US Federal Reserve (Fed), the European Central Bank (ECB) or the Bank of England (BoE), the mandate is to keep inflation close to 2%.
A central bank has one important tool at its disposal to get inflation higher or lower, and that is by tweaking its benchmark policy rate, commonly known as interest rate. On pre-communicated moments, the central bank will issue a statement with its policy rate and provide additional reasoning on why it is either remaining or changing (cutting or hiking) it. Local banks will adjust their savings and lending rates accordingly, which in turn will make it either harder or easier for people to earn on their savings or for companies to take out loans and make investments in their businesses. When the central bank hikes interest rates substantially, this is called monetary tightening. When it is cutting its benchmark rate, it is called monetary easing.
A central bank is often politically independent. Members of the central bank policy board are passing through a series of panels and hearings before being appointed to a policy board seat. Each member in that board often has a certain conviction on how the central bank should control inflation and the subsequent monetary policy. Members that want a very loose monetary policy, with low rates and cheap lending, to boost the economy substantially while being content to see inflation slightly above 2%, are called ‘doves’. Members that rather want to see higher rates to reward savings and want to keep a lit on inflation at all time are called ‘hawks’ and will not rest until inflation is at or just below 2%.
Normally, there is a chairman or president who leads each meeting, needs to create a consensus between the hawks or doves and has his or her final say when it would come down to a vote split to avoid a 50-50 tie on whether the current policy should be adjusted. The chairman will deliver speeches which often can be followed live, where the current monetary stance and outlook is being communicated. A central bank will try to push forward its monetary policy without triggering violent swings in rates, equities, or its currency. All members of the central bank will channel their stance toward the markets in advance of a policy meeting event. A few days before a policy meeting takes place until the new policy has been communicated, members are forbidden to talk publicly. This is called the blackout period.
Author

Vishal Chaturvedi
FXStreet
I am a macro-focused research analyst with over four years of experience covering forex and commodities market. I enjoy breaking down complex economic trends and turning them into clear, actionable insights that help traders stay ahead of the curve.

















