Dollar Index slips from its 18-month high before US CPI
- DXY gives back most of Monday's climb to an 18-month high as Brent eases.
- US CPI is due Wednesday, and traders already fully expect a December Fed hike.
The September Consumer Price Index (CPI) is due on Wednesday at 12:30 GMT, with headline inflation forecast to rise to 3.6% from 3.4%. Core prices, which leave out food and energy, are forecast up 0.2% in the month against 0.6% overall. Traders fully expect a quarter-point Fed hike in December, and some analysts reckon a 0.4% monthly core reading would pull it forward to the October 27-28 meeting.
Higher US yields pay investors more to hold Dollars than Euros or Yen, and the 10-year Treasury yield, near 5.2%, is close to a 24-year high. Fed Governor Waller said the climb reflects growth, not inflation, and cited research that Treasuries have lost part of their convenience yield, the lower rate investors accept for the safety of US debt. He put the cost at 0.5 to 0.7 points, so part of the extra pay for holding Dollars compensates for lending to Washington at all.
Brent slipped back under $106 from Monday's high above $107 on expectations of more Russian diesel supply. A cheaper barrel means European and Japanese importers buy fewer Dollars to pay for it, reversing the flow behind Monday's high.
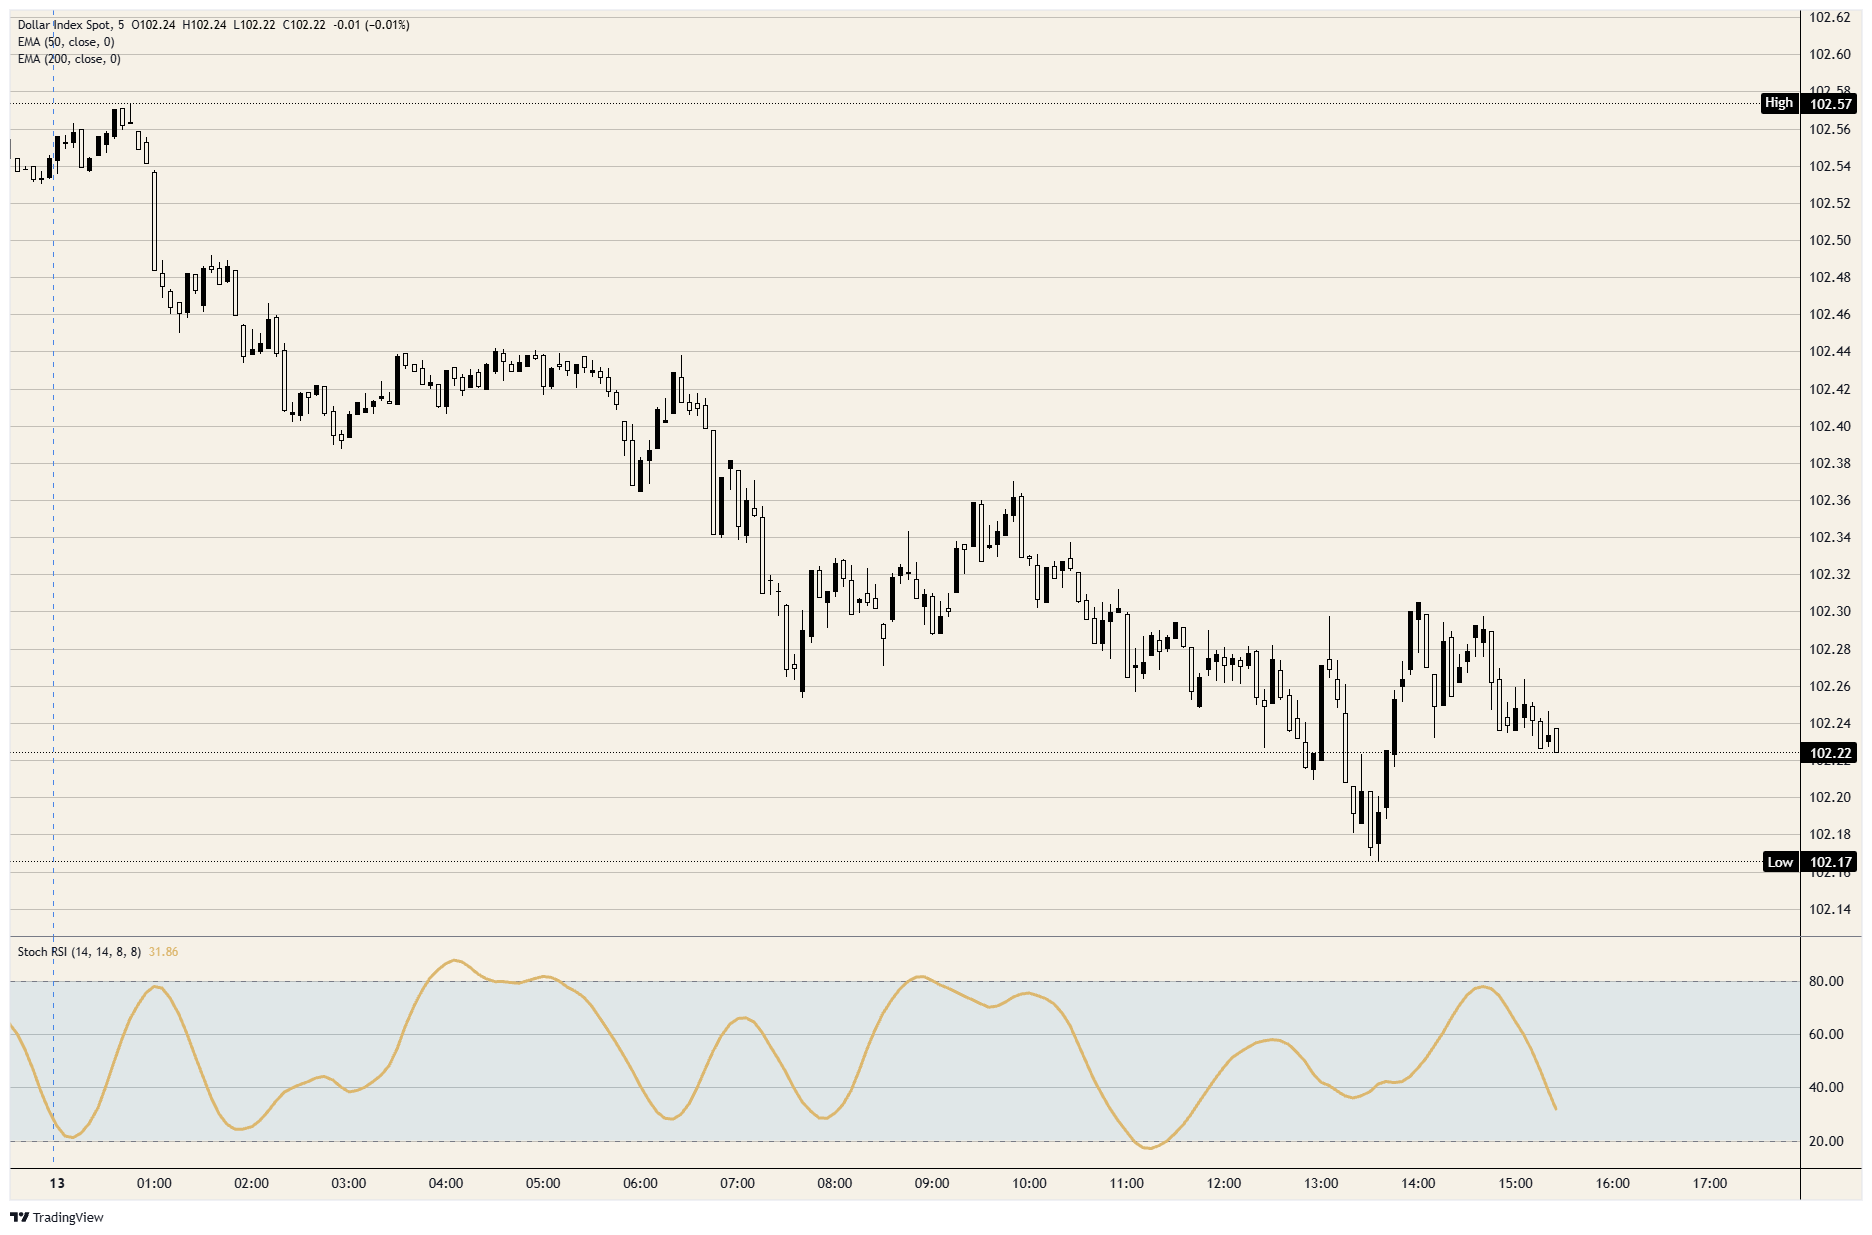
The Dollar Index fell from just under 102.60 to a low just under 102.20, giving back most of Monday's climb to just above 102.60, its highest since April 2025. It fell in steps through the session rather than on any one release, and the bounce off the low to 102.30 faded.
On the charts
The index is trading near 102.20, close to Tuesday's low and well above the 50-day Exponential Moving Average (EMA) near 100.70. The drop is about a tenth of the climb from the September 9 low near 98.60 to Monday's high. Daily momentum is still overbought after that run and has been cooling since early October.
DXY 5-minute chart
US Dollar FAQs
The US Dollar (USD) is the official currency of the United States of America, and the ‘de facto’ currency of a significant number of other countries where it is found in circulation alongside local notes. It is the most heavily traded currency in the world, accounting for over 88% of all global foreign exchange turnover, or an average of $6.6 trillion in transactions per day, according to data from 2022. Following the second world war, the USD took over from the British Pound as the world’s reserve currency. For most of its history, the US Dollar was backed by Gold, until the Bretton Woods Agreement in 1971 when the Gold Standard went away.
The most important single factor impacting on the value of the US Dollar is monetary policy, which is shaped by the Federal Reserve (Fed). The Fed has two mandates: to achieve price stability (control inflation) and foster full employment. Its primary tool to achieve these two goals is by adjusting interest rates. When prices are rising too quickly and inflation is above the Fed’s 2% target, the Fed will raise rates, which helps the USD value. When inflation falls below 2% or the Unemployment Rate is too high, the Fed may lower interest rates, which weighs on the Greenback.
In extreme situations, the Federal Reserve can also print more Dollars and enact quantitative easing (QE). QE is the process by which the Fed substantially increases the flow of credit in a stuck financial system. It is a non-standard policy measure used when credit has dried up because banks will not lend to each other (out of the fear of counterparty default). It is a last resort when simply lowering interest rates is unlikely to achieve the necessary result. It was the Fed’s weapon of choice to combat the credit crunch that occurred during the Great Financial Crisis in 2008. It involves the Fed printing more Dollars and using them to buy US government bonds predominantly from financial institutions. QE usually leads to a weaker US Dollar.
Quantitative tightening (QT) is the reverse process whereby the Federal Reserve stops buying bonds from financial institutions and does not reinvest the principal from the bonds it holds maturing in new purchases. It is usually positive for the US Dollar.
Author

Joshua Gibson
FXStreet
Joshua joins the FXStreet team as an Economics and Finance double major from Vancouver Island University with twelve years' experience as an independent trader focusing on technical analysis.

















