Dollar Index hits an 18-month high as the energy ceasefire fails
- DXY breaks above 102.50 to its highest since April 2025 as Crude Oil rises.
- Russia hits six Ukrainian energy sites days after Trump's ceasefire claim.
US President Trump said on Friday that Russia and Ukraine had agreed to stop striking each other's energy sites, and Brent fell below $103 a barrel when markets reopened. Brent then climbed back as Russia kept striking Ukraine's energy facilities, six of them on Monday by Ukrainian President Zelenskyy's count. The Kremlin said the same day that ceasefire talks were still underway.
Europe and Japan import nearly all their Oil and pay for it in Dollars, so a dearer barrel means selling more Euros and Yen. The Euro and the Yen make up 71% of the Dollar Index and account for about three-quarters of its climb from the Monday low. The US cash bond market is shut for Columbus Day, so the 10-year Treasury yield hasn't moved from Friday's 5.24%.
Iran's Revolutionary Guards said on Monday they had set a third supertanker on fire in the Strait of Hormuz in two days. Brent reached just above $107, its highest in more than two weeks, on the claim, and the Dollar Index rose with it.
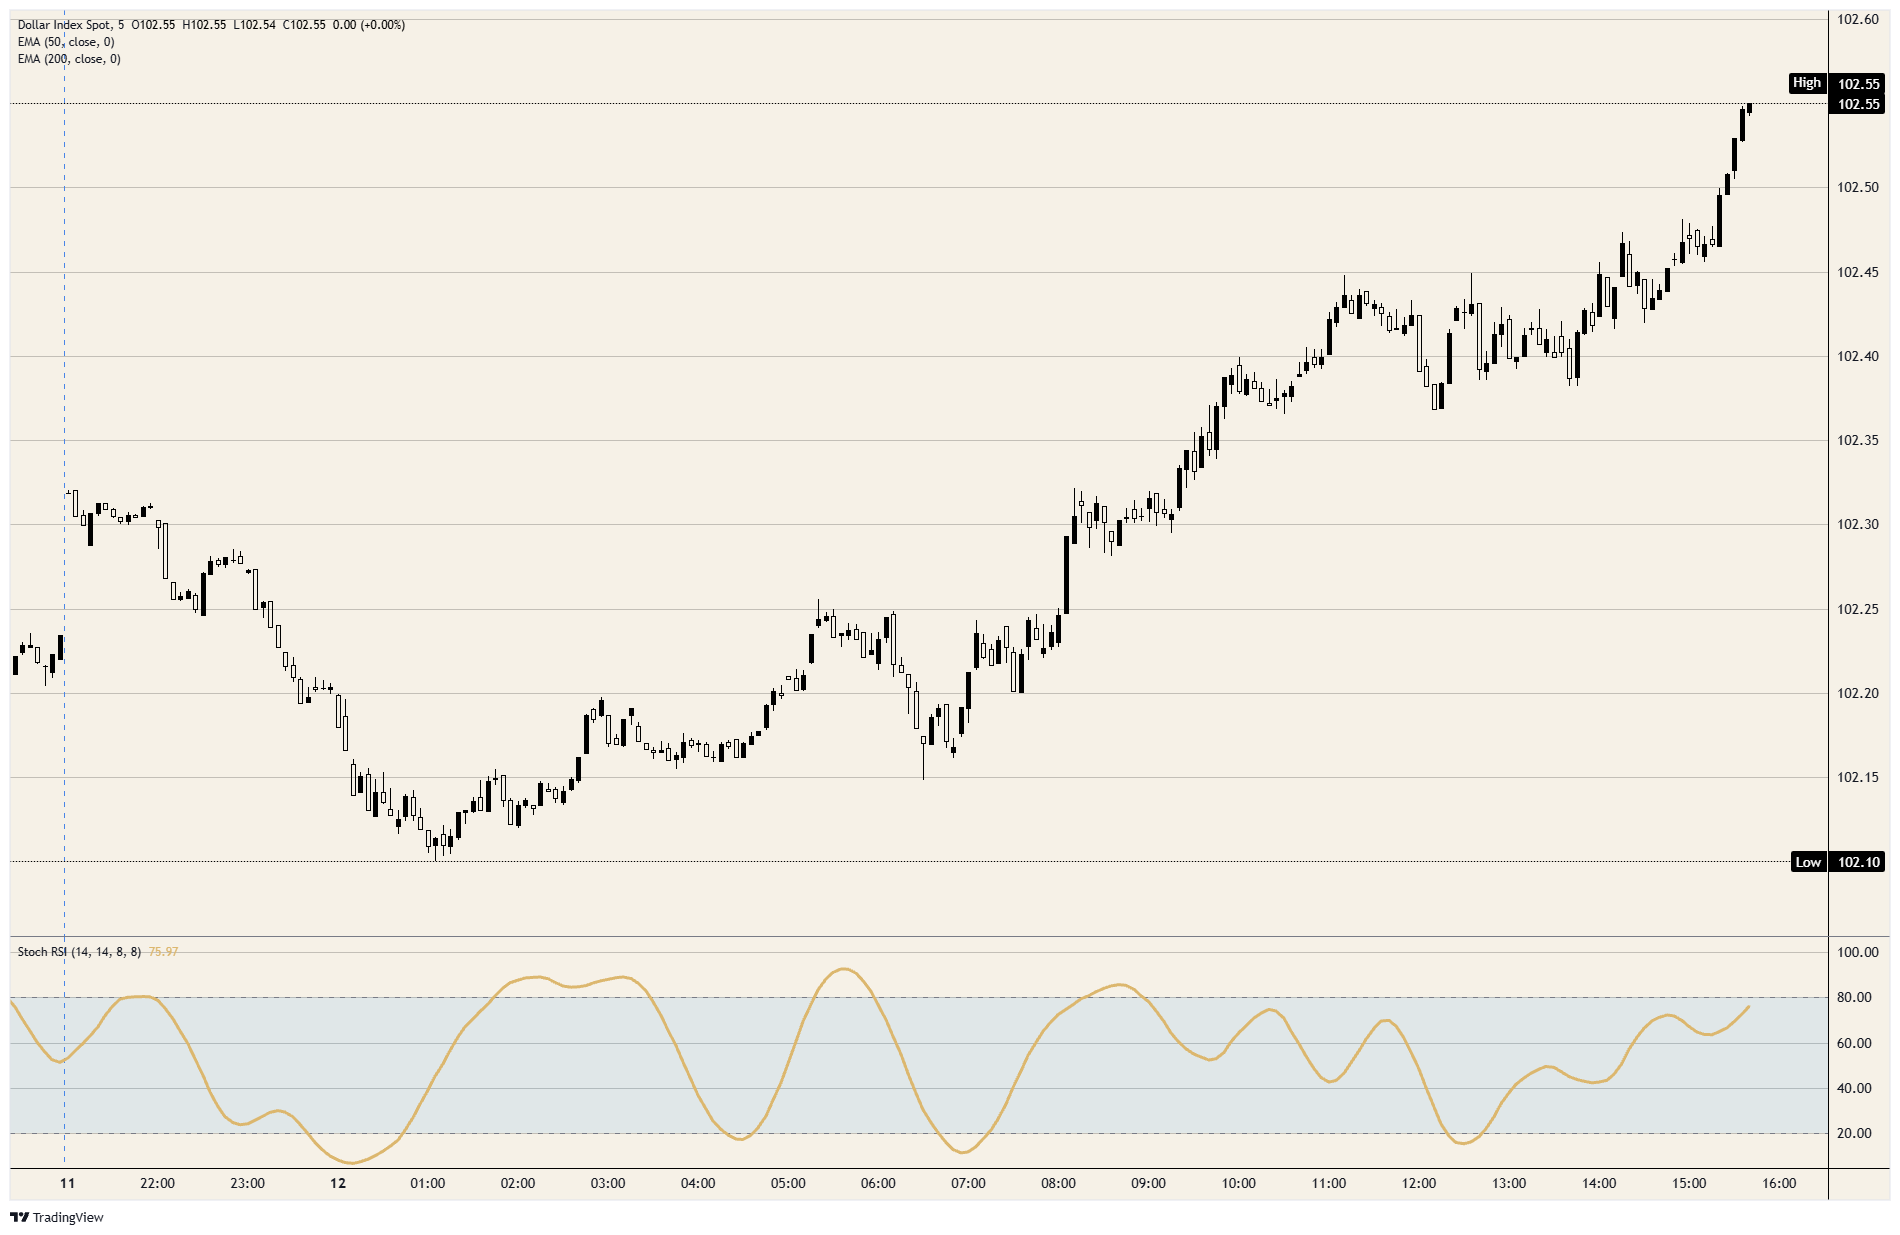
The index dropped to near 102.10 as Brent fell at the weekly open, then climbed in steps to just above 102.50, its highest since April 2025. The last step began on the tanker claim and carried on after Brent had levelled off, as the Euro slid further.
On the charts
The index is holding at its high, and every pullback since Monday's low has held above the previous one. It has gone through 102.50, the level that capped it on October 5, 7 and 8. The climb from the September 9 low is about 4% and follows four straight weekly gains.
DXY 5-minute chart
US Dollar FAQs
The US Dollar (USD) is the official currency of the United States of America, and the ‘de facto’ currency of a significant number of other countries where it is found in circulation alongside local notes. It is the most heavily traded currency in the world, accounting for over 88% of all global foreign exchange turnover, or an average of $6.6 trillion in transactions per day, according to data from 2022. Following the second world war, the USD took over from the British Pound as the world’s reserve currency. For most of its history, the US Dollar was backed by Gold, until the Bretton Woods Agreement in 1971 when the Gold Standard went away.
The most important single factor impacting on the value of the US Dollar is monetary policy, which is shaped by the Federal Reserve (Fed). The Fed has two mandates: to achieve price stability (control inflation) and foster full employment. Its primary tool to achieve these two goals is by adjusting interest rates. When prices are rising too quickly and inflation is above the Fed’s 2% target, the Fed will raise rates, which helps the USD value. When inflation falls below 2% or the Unemployment Rate is too high, the Fed may lower interest rates, which weighs on the Greenback.
In extreme situations, the Federal Reserve can also print more Dollars and enact quantitative easing (QE). QE is the process by which the Fed substantially increases the flow of credit in a stuck financial system. It is a non-standard policy measure used when credit has dried up because banks will not lend to each other (out of the fear of counterparty default). It is a last resort when simply lowering interest rates is unlikely to achieve the necessary result. It was the Fed’s weapon of choice to combat the credit crunch that occurred during the Great Financial Crisis in 2008. It involves the Fed printing more Dollars and using them to buy US government bonds predominantly from financial institutions. QE usually leads to a weaker US Dollar.
Quantitative tightening (QT) is the reverse process whereby the Federal Reserve stops buying bonds from financial institutions and does not reinvest the principal from the bonds it holds maturing in new purchases. It is usually positive for the US Dollar.
Author

Joshua Gibson
FXStreet
Joshua joins the FXStreet team as an Economics and Finance double major from Vancouver Island University with twelve years' experience as an independent trader focusing on technical analysis.
















