Breaking: Canada headline CPI came in at 2.8% in April
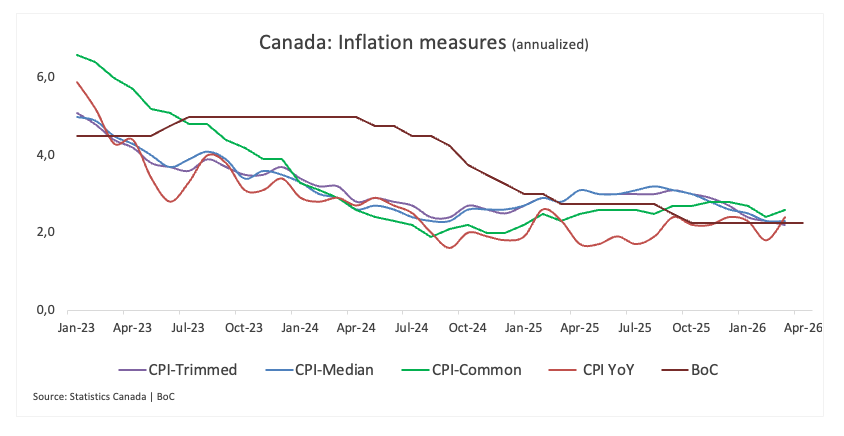
Canada’s inflation picked up pace in April, with the Consumer Price Index (CPI) rising 2.8% from a year earlier, below market expectations and up from the 2.4% increase recorded in March. On a monthly basis, prices rose 0.4%.
Meanwhile, the Bank of Canada’s (BoC) preferred core measure, which excludes more volatile components such as food and energy, rose 2.1% over the past year and increased by 0.2% compared with the previous month.
Looking at the BoC’s other key inflation gauges, Common CPI came in at 2.5% (from 2.6% ), Trimmed CPI at 2.0% (from 2.2%), and Median CPI at 2.1% (from 2.3%). Together, they show that underlying price pressures are still fairly sticky albeit on a downward trend.
According to the press release: “Higher energy prices, most notably gasoline prices, drove the acceleration in the headline CPI. The removal of the consumer carbon levy in April 2025, which resulted in monthly declines for gasoline and natural gas, has now fallen out of the 12-month movement, putting upward pressure on the all-items CPI. Excluding gasoline, the CPI rose at a slower pace year over year in April (+2.0%) compared with March (+2.2%).”
Market reaction
The Canadian Dollar (CAD) remains on the back foot on Tuesday, motivating USD/CAD to advance to new multi-week tops past 1.3770 in the wake of the release of domestic inflation data.
Canadian Dollar Price Today
The table below shows the percentage change of Canadian Dollar (CAD) against listed major currencies today. Canadian Dollar was the strongest against the Australian Dollar.
| USD | EUR | GBP | JPY | CAD | AUD | NZD | CHF | |
|---|---|---|---|---|---|---|---|---|
| USD | 0.33% | 0.16% | 0.16% | 0.23% | 0.69% | 0.48% | 0.40% | |
| EUR | -0.33% | -0.17% | -0.15% | -0.10% | 0.38% | 0.16% | 0.08% | |
| GBP | -0.16% | 0.17% | 0.02% | 0.07% | 0.52% | 0.34% | 0.25% | |
| JPY | -0.16% | 0.15% | -0.02% | 0.05% | 0.50% | 0.32% | 0.22% | |
| CAD | -0.23% | 0.10% | -0.07% | -0.05% | 0.45% | 0.26% | 0.17% | |
| AUD | -0.69% | -0.38% | -0.52% | -0.50% | -0.45% | -0.18% | -0.28% | |
| NZD | -0.48% | -0.16% | -0.34% | -0.32% | -0.26% | 0.18% | -0.10% | |
| CHF | -0.40% | -0.08% | -0.25% | -0.22% | -0.17% | 0.28% | 0.10% |
The heat map shows percentage changes of major currencies against each other. The base currency is picked from the left column, while the quote currency is picked from the top row. For example, if you pick the Canadian Dollar from the left column and move along the horizontal line to the US Dollar, the percentage change displayed in the box will represent CAD (base)/USD (quote).
This section below was published as a preview of the Canadian inflation report for April at 08:00 GMT.
- Canadian inflation is expected to rise by 3.1% YoY in April.
- The core CPI is still seen well above the BoC’s 2% target.
- The Canadian Dollar has been trading lower against the US Dollar recently.
The publication of Canada’s April Consumer Price Index (CPI) figures on Tuesday will be the focus of attention. Indeed, Statistics Canada data will provide the Bank of Canada (BoC) with a much-needed update on price pressures ahead of its June 10 meeting, where policymakers are widely expected to keep rates steady at 2.25%.
Economists see the headline CPI rising by 3.1% in a year to April, gathering pace above the BoC’s target and up from March’s 2.4% annual increase. On a monthly basis, prices are expected to rise by 0.8%. The bank will also closely monitor its core measure (which strips food and energy costs), which came in at 2.5% YoY in the previous month.
Policymakers remain uneasy, as increasing risks of US tariffs and the ongoing crisis in the Middle East feeding into domestic prices are adding another layer of uncertainty.
What can we expect from Canada’s inflation rate?
No one is expecting inflation to remain unchanged, let alone lose momentum, in April. Against this backdrop, and mirroring what has happened in the US following hotter-than-estimated CPI data last month, the Bank of Canada should reinforce its cautious stance and lean further toward its data-dependent point of view.
Indeed, the central bank is expected to maintain its steady hand at its June 10 gathering, following four consecutive ‘on hold’ decisions, although a higher-for-longer view of domestic consumer prices could open the door to a tighter monetary policy.
At its latest event, the BoC signalled an upbeat medium-term outlook for economic growth while revising inflation higher for the current year. In addition, Governor Tiff Macklem delivered a cautious message at his press conference, keeping the data-dependent stance well in place while leaving the door open to higher rates in case energy prices remain elevated.
So far, market participants expect just over 50 basis points of tightening by year-end.
Additionally, the bank’s preferred gauges, CPI-Common, Trimmed Mean, and Median, also moderated, but at 2.6%, 2.2%, and 2.3%, respectively, they continued to run above the 2% objective.
When is the Canada CPI data due, and how could it affect USD/CAD?
Markets will fully focus on Tuesday at 12:30 GMT, when Statistics Canada publishes April’s inflation figures. There’s a sense of nervous anticipation, with traders wary that price pressures might gather traction and keep monetary conditions pretty tight.
Pablo Piovano, Senior Analyst at FXStreet, notes that USD/CAD has been on a steady uptrend since the beginning of the month, almost entirely tracking developments from the Middle East conflicts and the US Dollar’s (USD) price action.
Piovano points out that USD/CAD seems to have met some resistance around monthly tops near 1.3770. Once this area is cleared, the pair could embark on a potential trip toward its significant 200-day SMA around 1.3810.
On the flip side, he highlights initial support at the May floor of 1.3549 (May 1), seconded by the March base at 1.3525 (March 9), the February valley at 1.3504 (February 11) and the 2026 bottom at 1.3481 (January 30).
“Momentum appears mixed,” he adds, noting that the Relative Strength Index (RSI) is navigating just below the 59 level, although the Average Directional Index (ADX) near 17 suggests the underlying trend still lacks juice.
Bank of Canada FAQs
The Bank of Canada (BoC), based in Ottawa, is the institution that sets interest rates and manages monetary policy for Canada. It does so at eight scheduled meetings a year and ad hoc emergency meetings that are held as required. The BoC primary mandate is to maintain price stability, which means keeping inflation at between 1-3%. Its main tool for achieving this is by raising or lowering interest rates. Relatively high interest rates will usually result in a stronger Canadian Dollar (CAD) and vice versa. Other tools used include quantitative easing and tightening.
In extreme situations, the Bank of Canada can enact a policy tool called Quantitative Easing. QE is the process by which the BoC prints Canadian Dollars for the purpose of buying assets – usually government or corporate bonds – from financial institutions. QE usually results in a weaker CAD. QE is a last resort when simply lowering interest rates is unlikely to achieve the objective of price stability. The Bank of Canada used the measure during the Great Financial Crisis of 2009-11 when credit froze after banks lost faith in each other’s ability to repay debts.
Quantitative tightening (QT) is the reverse of QE. It is undertaken after QE when an economic recovery is underway and inflation starts rising. Whilst in QE the Bank of Canada purchases government and corporate bonds from financial institutions to provide them with liquidity, in QT the BoC stops buying more assets, and stops reinvesting the principal maturing on the bonds it already holds. It is usually positive (or bullish) for the Canadian Dollar.
Economic Indicator
BoC Consumer Price Index Core (YoY)
The BoC Consumer Price Index Core, released by the Bank of Canada (BoC) on a monthly basis, represents changes in prices for Canadian consumers by comparing the cost of a fixed basket of goods and services. It is considered a measure of underlying inflation as it excludes eight of the most-volatile components: fruits, vegetables, gasoline, fuel oil, natural gas, mortgage interest, intercity transportation and tobacco products. The YoY reading compares prices in the reference month to the same month a year earlier. Generally, a high reading is seen as bullish for the Canadian Dollar (CAD), while a low reading is seen as bearish.
Read more.Next release: Tue May 19, 2026 12:30
Frequency: Monthly
Consensus: -
Previous: 2.5%
Source: Statistics Canada
Author

FXStreet Team
FXStreet
Composed of a group of economic journalists and FX experts, the FXStreet content team produces and oversees all content published on FXStreet. It provides a purely journalistic approach to the Forex market.

















