British Pound Sterling's three-month high was made in America
- GBP/USD trades just short of 1.3550, its strongest level since early May.
- UK unemployment holds at 4.9% against 4.8% expected, employment growth halved.
- September Fed hike odds near 31%, down from above 82% in late July.
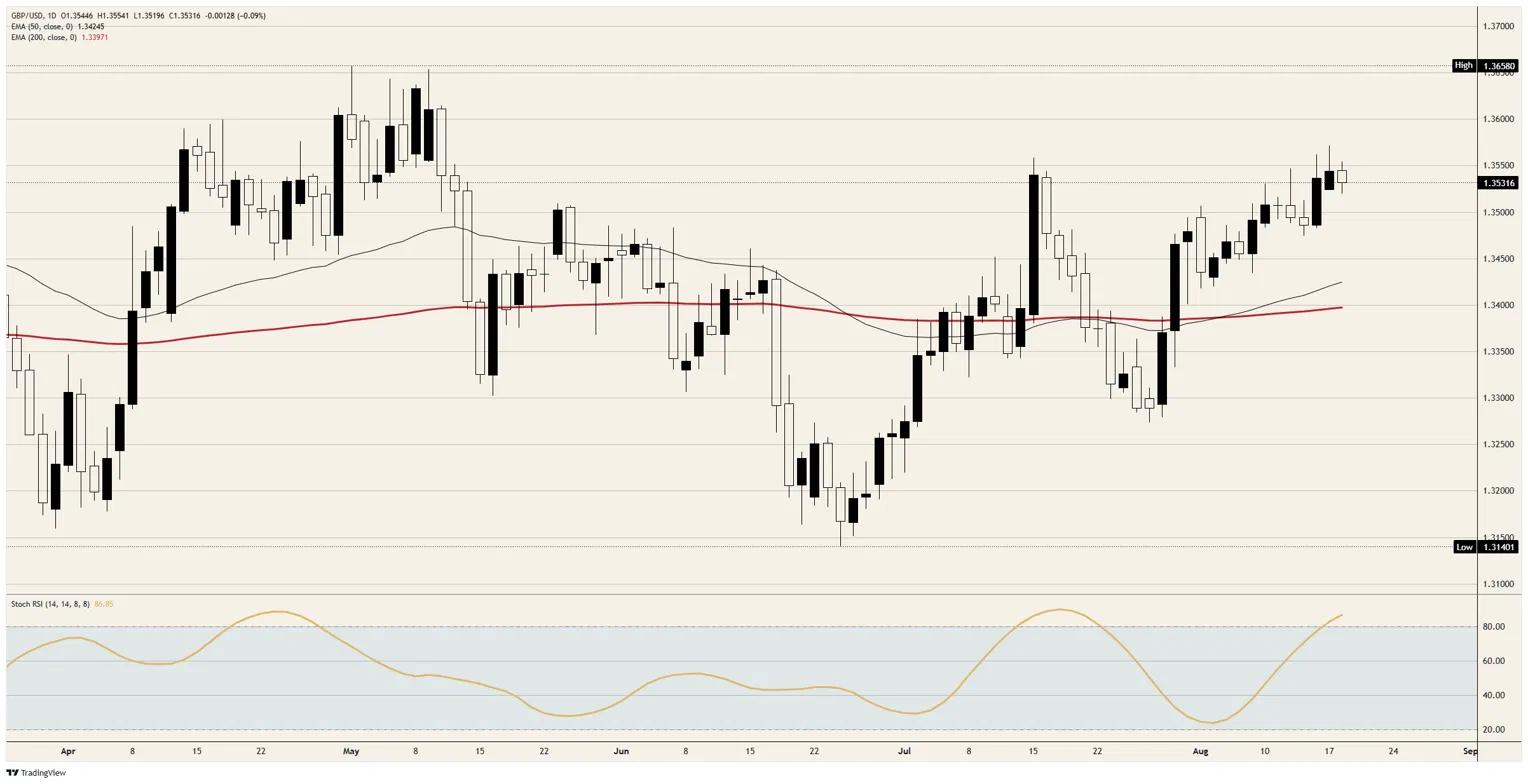
The British Pound trades just short of 1.3550 against the Dollar on Tuesday, holding inside Monday's range after a peak short of 1.3600 carried it to its strongest level since early May. That leaves close to 300 pips of recovery from the base just short of 1.3300 built in the first week of August.
The advance has taken the rate back above both major moving averages and pushed the shorter one above the longer for the first time since spring, which is a change of structure rather than a bounce. What it has not involved is any material contribution from Britain. Tuesday's labour market release was the first red-band domestic event in three weeks, and the currency answered it with a 35-pip range and a small loss.
The jobs report cooled in the direction that counts
Regular pay growth, the series the Monetary Policy Committee (MPC) treats as the cleanest read on domestically generated inflation, accelerated to 3.5% in the three months to June from 3.4%, a tenth above consensus. Total pay including bonuses eased to 4.1% from 4.4%. Pay at that pace still sits above the 3.3% the committee pencilled in for the fourth quarter back in February, so on price the release handed the hawks a marginal win.
On quantity the same release handed them nothing at all, with employment growth over those three months nearly halving to 83K from 147K and the unemployment rate holding at 4.9% where a decline to 4.8% was expected. Vacancies slipped to 707K on the May to July estimate, the weakest reading outside the pandemic since late 2014. July's claimant count fell 11K against an expected rise above 11K, the single line in the release that argues the other way.
The rally carries an American passport
Almost the entire August advance belongs to the other side of the quote, where futures now price a September Federal Reserve increase near 31%, down from above 82% in the days after the July 29 decision, a collapse delivered by three consecutive American releases: payrolls contracting 23K, July Consumer Price Index (CPI) at 3.4% YoY with core at 2.5%, and retail sales falling 0.6%.
Sterling's own rate story has barely shifted across the same three weeks, which is what makes the attribution awkward. Swap pricing puts a hold at the September 17 MPC decision near 72%, with roughly 7 basis points of tightening in that meeting and about 30 basis points by year-end.
That curve was built on the energy shock rather than on anything the domestic data has delivered, and Tuesday's numbers gave it no fresh support. The Pound is not being bought. The Dollar is being sold, and the autumn Budget in October still sits beyond the horizon of every forecast currently in the price. Renewed tension around the Strait of Hormuz put a modest bid back under the Dollar on Tuesday, which accounts for most of the session's small decline.
Wednesday hands the Pound its first domestic test
July inflation lands at 06:00 GMT on Wednesday, August 19, with consensus at 2.9% YoY on the headline against 2.6% in June, and 0.3% MoM against 0.1%. Core is forecast a tenth lower at 2.5%. The shape of that combination matters more than either number, because a headline pushed up by energy while core drifts down is the easiest hold the September meeting could ask for.
Services inflation ran at 3.6% in June and remains the component the committee actually reads, so the reaction function sits well below the headline. The rest of the British calendar runs the same way. Producer prices arrive alongside the inflation release, consumer confidence is forecast to slip to -18 on Thursday, and Friday brings July retail sales expected at -0.5% MoM after a 1% gain, with all three preliminary August Purchasing Managers Index (PMI) readings forecast lower.
Wednesday's 18:00 GMT release of the Federal Open Market Committee (FOMC) minutes is the other half of the equation, and it covers a meeting held three weeks before every print that repriced September. Those minutes carry a record of an argument rather than a forecast, and the Dollar will trade the conditions attached to that argument rather than the vote itself.
Levels to watch
Resistance: Monday's peak short of 1.3600 is the line that matters, and a daily close above it opens the early-May high near 1.3650 with little standing in between. The 1.3550 shelf caps in the interim.
Support: The 1.3500 handle contained Tuesday's low and marks the first shelf. Beneath it, both moving averages now sit stacked in a band between 1.3400 and 1.3450, which is where the August trend gets its first genuine test.
Bias: Bullish. The moving-average band has flipped to support and price holds a clear cent above it, so pullbacks into 1.3450 are for buying rather than fading. The caveat is momentum, with the daily Stochastic Relative Strength Index (Stoch RSI) near 87 and a domestic calendar heavy enough to break the trend. A daily close beneath 1.3400 invalidates.
GBP/USD daily chart
Pound Sterling FAQs
The Pound Sterling (GBP) is the oldest currency in the world (886 AD) and the official currency of the United Kingdom. It is the fourth most traded unit for foreign exchange (FX) in the world, accounting for 12% of all transactions, averaging $630 billion a day, according to 2022 data. Its key trading pairs are GBP/USD, also known as ‘Cable’, which accounts for 11% of FX, GBP/JPY, or the ‘Dragon’ as it is known by traders (3%), and EUR/GBP (2%). The Pound Sterling is issued by the Bank of England (BoE).
The single most important factor influencing the value of the Pound Sterling is monetary policy decided by the Bank of England. The BoE bases its decisions on whether it has achieved its primary goal of “price stability” – a steady inflation rate of around 2%. Its primary tool for achieving this is the adjustment of interest rates. When inflation is too high, the BoE will try to rein it in by raising interest rates, making it more expensive for people and businesses to access credit. This is generally positive for GBP, as higher interest rates make the UK a more attractive place for global investors to park their money. When inflation falls too low it is a sign economic growth is slowing. In this scenario, the BoE will consider lowering interest rates to cheapen credit so businesses will borrow more to invest in growth-generating projects.
Data releases gauge the health of the economy and can impact the value of the Pound Sterling. Indicators such as GDP, Manufacturing and Services PMIs, and employment can all influence the direction of the GBP. A strong economy is good for Sterling. Not only does it attract more foreign investment but it may encourage the BoE to put up interest rates, which will directly strengthen GBP. Otherwise, if economic data is weak, the Pound Sterling is likely to fall.
Another significant data release for the Pound Sterling is the Trade Balance. This indicator measures the difference between what a country earns from its exports and what it spends on imports over a given period. If a country produces highly sought-after exports, its currency will benefit purely from the extra demand created from foreign buyers seeking to purchase these goods. Therefore, a positive net Trade Balance strengthens a currency and vice versa for a negative balance.
Author

Joshua Gibson
FXStreet
Joshua joins the FXStreet team as an Economics and Finance double major from Vancouver Island University with twelve years' experience as an independent trader focusing on technical analysis.

















