A two-decade yield high buys the Dollar Index nothing
- DXY holds just above 99.50 inside a 17-pip session range.
- December Fed hike odds slip to 67%, from fully priced on August 10.
- Long ends at multi-decade highs in Tokyo, Berlin and Paris alike.
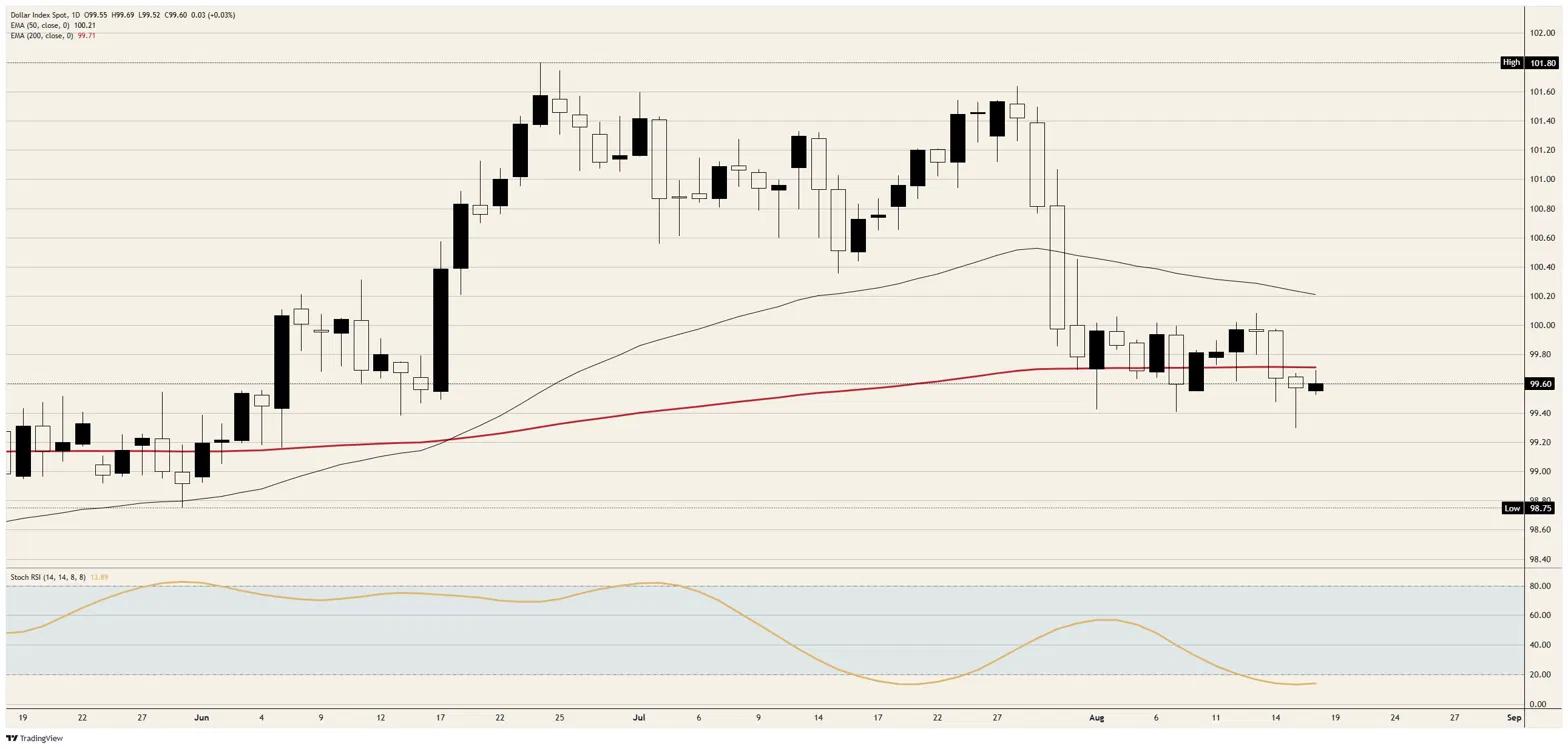
The highest long-dated US yields in nearly two decades have moved the US Dollar Index (DXY) by three hundredths of a point. Spot holds just above 99.50 on Tuesday after a session range of 17 pips, still beneath a flat 200-day Exponential Moving Average (EMA) near 99.75 that has capped every attempt for a fortnight.
The differential that never opened
A thirty-year Treasury yield around 5.3%, its highest since June 2007, would ordinarily be a Dollar story on its own. It is not one here, because the same move is happening everywhere. Japan's 10-year sits at a three-decade high, Germany's 30-year at its firmest since 2011 and France's 30-year at levels unseen since 2008, with the United Kingdom, Italy, Switzerland and Canada all higher.
Currency is a relative price and this is an absolute move. Yields lift a currency only when they rise faster than the other side of the pair, and a synchronised widening in term premium opens no gap for anyone. The index carries a 57.6% euro weight, so a German long end selling in step with the American one neutralises more than half the basket before the other five currencies are counted.
The Japanese leg is worse than neutral. At a 13.6% weight, a domestic bond yielding more than it has in thirty years gives the largest pool of overseas capital in the world a reason to bring money home rather than fund carry with it. Add the sterling and Canadian Dollar weights, both sitting on long ends of their own that are higher of late, and better than 80% of the basket is being repriced by the same force.
The one leg that moves the Dollar is going backwards
Policy expectations are the part of the curve that reliably prices a currency, and they are moving against the Dollar. Conditional meeting probabilities put a September 16 hold at 65.4% and an October 28 hold at 52.4%, with the December 9 hold cell at 33.0%. On August 10 a December increase was priced as a certainty.
Roughly a third of the terminal tightening has gone in eight days, and the below-band column stays empty at every 2026 meeting, printing nothing until well into 2027. This is not an easing cycle arriving. It is a hiking cycle being deferred, which strips the carry case from the Dollar without handing it a growth scare to shelter behind.
Tuesday's releases gave the deferral no argument. July housing starts printed 1.239 million against a 1.35 million consensus and 1.415 million prior, pending home sales fell 2.3% where a 0.3% gain was expected, and industrial production came in at 0.2% against 0.3%. Only Monday's August Empire State manufacturing index ran hot at 20.6 against 11, and survey optimism is not what a rate market discounts.
No haven bid either
Risk appetite deteriorated through Asian and European hours on the same headlines that lifted the long end, with Crude Oil pushing above the $85.00 handle after Washington confirmed no talks with Iran are underway or scheduled and that the naval blockade holds. On any of the past five years of correlations that is a Dollar-positive combination, and the basket did not move.
A 17-pip range under those conditions is not calm but a market with nothing left to express, having already sold the Dollar from a late-June peak near 101.75 into a fortnight of chop around the 200-day EMA. The daily Stochastic Relative Strength Index (Stoch RSI) reads near 14, pinned at the floor of its band for a second week without producing a bounce, which describes sellers who are patient rather than exhausted.
What is left this week
The Federal Open Market Committee (FOMC) minutes from the July 28-29 meeting land Wednesday at 18:00 GMT and carry the week's first red band. Three reserve bank presidents dissented for a quarter point at that meeting, and the market has spent the three weeks since deleting the increase they voted for, so the minutes read as a test of how isolated that bloc really was.
Thursday brings initial jobless claims against a 210K consensus and 209K prior, with a Philadelphia Fed manufacturing survey forecast to halve to 25 from 41.4. Friday's preliminary August Purchasing Managers Index (PMI) readings are the second red band and the only survey this week with the breadth to move September pricing, manufacturing seen at 53.8 from 53.9 and services at 54 from 54.6.
Dollar Index levels
Resistance: The 200-day EMA near 99.75 caps immediately, with the 100.00 handle above it and the declining 50-day EMA near 100.25 the line that would end this downtrend.
Support: 99.50 is the session floor in play, and a break there opens 99.25, with the late-May base near 98.75 the objective beneath.
Bias: Bearish. The Dollar is losing the only rate leg that pays it while the global long end reprices in lockstep, and a 17-pip range beneath a flat 200-day EMA is compression resolving lower rather than a base forming. Invalidation comes on a daily close above 100.25.
DXY daily chart
US Dollar FAQs
The US Dollar (USD) is the official currency of the United States of America, and the ‘de facto’ currency of a significant number of other countries where it is found in circulation alongside local notes. It is the most heavily traded currency in the world, accounting for over 88% of all global foreign exchange turnover, or an average of $6.6 trillion in transactions per day, according to data from 2022. Following the second world war, the USD took over from the British Pound as the world’s reserve currency. For most of its history, the US Dollar was backed by Gold, until the Bretton Woods Agreement in 1971 when the Gold Standard went away.
The most important single factor impacting on the value of the US Dollar is monetary policy, which is shaped by the Federal Reserve (Fed). The Fed has two mandates: to achieve price stability (control inflation) and foster full employment. Its primary tool to achieve these two goals is by adjusting interest rates. When prices are rising too quickly and inflation is above the Fed’s 2% target, the Fed will raise rates, which helps the USD value. When inflation falls below 2% or the Unemployment Rate is too high, the Fed may lower interest rates, which weighs on the Greenback.
In extreme situations, the Federal Reserve can also print more Dollars and enact quantitative easing (QE). QE is the process by which the Fed substantially increases the flow of credit in a stuck financial system. It is a non-standard policy measure used when credit has dried up because banks will not lend to each other (out of the fear of counterparty default). It is a last resort when simply lowering interest rates is unlikely to achieve the necessary result. It was the Fed’s weapon of choice to combat the credit crunch that occurred during the Great Financial Crisis in 2008. It involves the Fed printing more Dollars and using them to buy US government bonds predominantly from financial institutions. QE usually leads to a weaker US Dollar.
Quantitative tightening (QT) is the reverse process whereby the Federal Reserve stops buying bonds from financial institutions and does not reinvest the principal from the bonds it holds maturing in new purchases. It is usually positive for the US Dollar.
Author

Joshua Gibson
FXStreet
Joshua joins the FXStreet team as an Economics and Finance double major from Vancouver Island University with twelve years' experience as an independent trader focusing on technical analysis.

















