A BoJ hold is expected Friday after the Yen gives back half its gain
- USD/JPY wins back about half of its two-session drop and ends above 157.50.
- None of the economists in a Bloomberg survey expects a BoJ hike in October.
- Tokyo CPI and the BoJ's decision both follow Wednesday's Fed statement.
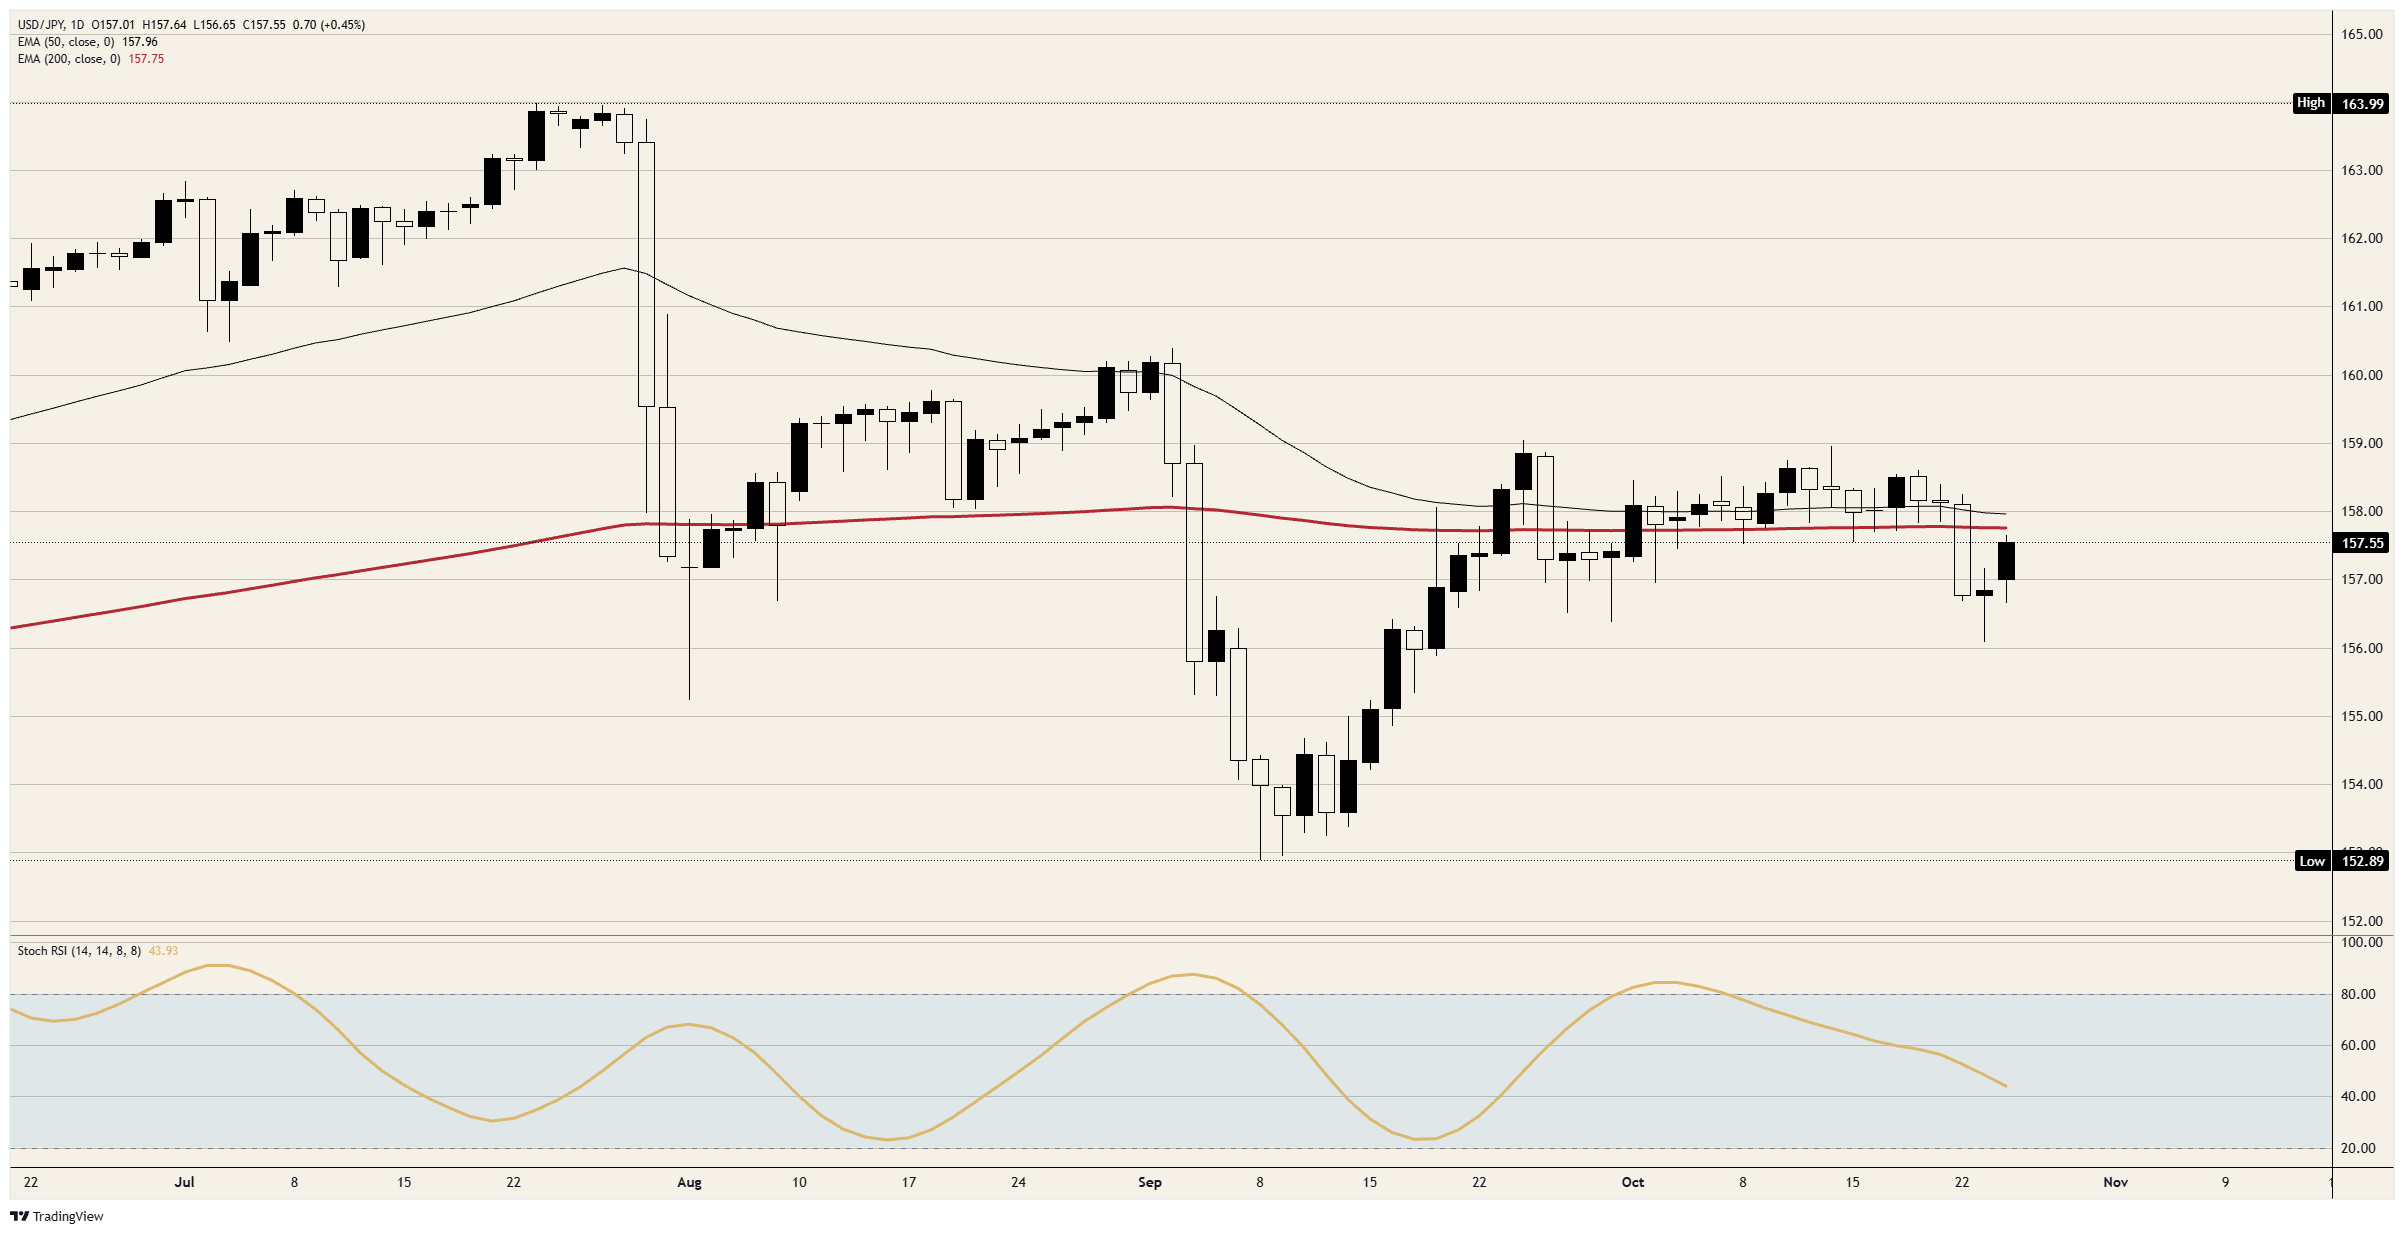
Monday's rise won back about half of what USD/JPY lost on October 22 and 23. Yen buying in Tokyo had taken it through 157.00 to its lowest since September 18. On Monday it rose from just above 156.50 to just above 157.50 and ended near its high for the session, two days before the Fed's decision.
The Bank of Japan (BoJ) raised its rate to 1.25% from 1% in September, and BoJ Governor Ueda has said there's no need for back-to-back hikes. With September's hike done, back-to-back would mean Friday, so the Yen isn't expected to get a BoJ hike to trade. None of the economists in a Bloomberg survey expects one in October, and most expect December.
September's vote was 7-2, with both dissents against raising rates. Previews expect any dissent on Friday to come from BoJ board members Takata and Tamura, in favour of a hike. A vote for one could bring forward the December hike the Yen is waiting on.
On the calendar
Tokyo's October Consumer Price Index (CPI) and Japan's September jobless rate are both out on Thursday at 23:30 GMT, the last figures before the BoJ's decision on Friday. BoJ Governor Ueda's press conference follows at 06:30 GMT on Friday, and his guidance on December is what USD/JPY has left to price from Tokyo.
The Fed is expected to hold its 3.75%-4.00% range when its statement comes out at 18:00 GMT Wednesday. US growth for the third quarter and the Personal Consumption Expenditures Price Index (PCE) for September follow at 12:30 GMT Thursday. Both shape the case for a December Fed hike.
On the charts
Monday's high stopped short of both moving averages, the 200-day Exponential Moving Average (EMA) and the 50-day, which are just under 158.00. The October 22 drop was the first daily close below 157.00 since September 18. The six-month range on the chart runs from the September 8 low just under 153.00 to the July high just under 164.00.
USD/JPY daily chart
Japanese Yen FAQs
The Japanese Yen (JPY) is one of the world’s most traded currencies. Its value is broadly determined by the performance of the Japanese economy, but more specifically by the Bank of Japan’s policy, the differential between Japanese and US bond yields, or risk sentiment among traders, among other factors.
One of the Bank of Japan’s mandates is currency control, so its moves are key for the Yen. The BoJ has directly intervened in currency markets sometimes, generally to lower the value of the Yen, although it refrains from doing it often due to political concerns of its main trading partners. The BoJ ultra-loose monetary policy between 2013 and 2024 caused the Yen to depreciate against its main currency peers due to an increasing policy divergence between the Bank of Japan and other main central banks. More recently, the gradually unwinding of this ultra-loose policy has given some support to the Yen.
Over the last decade, the BoJ’s stance of sticking to ultra-loose monetary policy has led to a widening policy divergence with other central banks, particularly with the US Federal Reserve. This supported a widening of the differential between the 10-year US and Japanese bonds, which favored the US Dollar against the Japanese Yen. The BoJ decision in 2024 to gradually abandon the ultra-loose policy, coupled with interest-rate cuts in other major central banks, is narrowing this differential.
The Japanese Yen is often seen as a safe-haven investment. This means that in times of market stress, investors are more likely to put their money in the Japanese currency due to its supposed reliability and stability. Turbulent times are likely to strengthen the Yen’s value against other currencies seen as more risky to invest in.
Author

Joshua Gibson
FXStreet
Joshua joins the FXStreet team as an Economics and Finance double major from Vancouver Island University with twelve years' experience as an independent trader focusing on technical analysis.