Weekly economic and financial commentary: Will the ECB start to taper?

Summary
United States: Supplies Attack
- Napoleon famously observed that an army marches on its stomach; in a similar vein, an economy can grow only as fast as its supply chains.
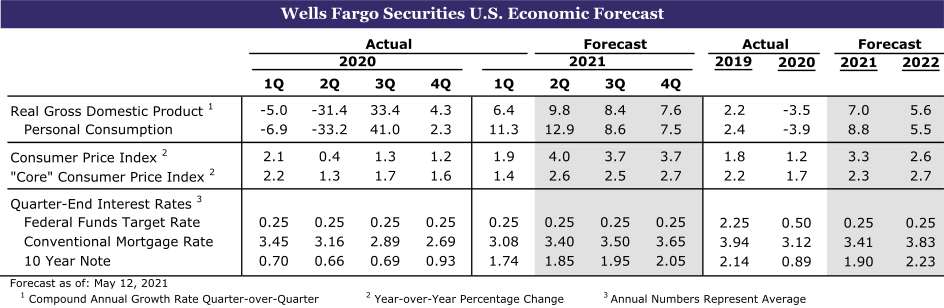
- Material shortages were evident in the ISM reports, and the May jobs report revealed labor shortages. Employers added 559K jobs, which was short of expectations. The fact that average hourly earnings jumped again points to the fact that employers are paying up to find talent.
- Next week: Trade Balance (Tuesday), CPI (Thursday)
International: Emerging Markets Growth Outperforming Early
- Q1 GDP prints were mixed this week as Canadian data underwhelmed relative to consensus expectations, while the Brazilian and Indian economies proved to be more resilient despite COVID-related headwinds.
- Next week: Brazil Inflation (Wednesday), Mexico Bi-Weekly CPI (Wednesday), Peru Elections (Sunday)
Interest Rate Watch: Will the ECB Start to Taper?
- The European Central Bank holds a widely anticipated policy meeting next week. Will the Governing Council announce a "tapering" in the pace of its asset purchases?
Credit Market Insights: So Long, SMCCF
- The Federal Reserve announced this week that it plans to wind down its corporate debt portfolio. The Secondary Market Corporate Credit Facility has roughly $14 billion in corporate bonds and corporate bond ETFs, and the unwinding of this portfolio is unlikely to have much direct impact on the broader corporate bond market.
Author

Wells Fargo Research Team
Wells Fargo
More from Wells Fargo Research Team