EUR holds 1.0500, US Dollar Index uptrend pauses, Fed readies 0.5 bp rate hike

EMFX Rebound on Month-End Adjustments; US Yields Soar, Stocks Fall
Summary: The Dollar Index (USD/DXY) which measures the value of the Greenback against a basket of 6 major currencies eased 0.4% to 103.21 (103.65) on month-end adjustments. Speculators took the opportunity to pare their Dollar long bets ahead of this week’s US Federal Reserve monetary policy meeting (Thursday, 5 May at 4 am Sydney). The latest data on market positioning from the CFTC (US Commodity Futures Trading Commission) and Reuters, the net long US Dollar position climbed to USD 13.92 billion in the week ended 26 April from USD 12.91 billion the previous week. In the month of April, the Greenback gained nearly 5%, its largest month advance since January 2015. Which saw the Dollar Index (DXY) spike to 19-year highs at 103.93 on Thursday before easing.
The Euro (EUR/USD) held the 1.0500 support level, rallying at the close of trade in New York to 1.0545 (1.0500 Friday). Against the Japanese Yen, the Greenback tumbled 0.95% to 129.85 from 130.85 despite higher US bond yields. The British Pound (GBP/USD) rebounded 0.7% to 1.2575 from 1.2560. However, the Australian Dollar (AUD/USD) dipped to 0.7060 from 0.7098 after commodity prices slumped. Against the Asian and Emerging Market currencies, the US Dollar was mostly lower. USD/THB fell 0.51% to 34.27 from 34.45 while the USD/CNH pair (Dollar-Offshore Chinese Yuan) slid to 6.6400 (6.6575 Friday). The USD/SGD pair dipped to 1.3831 (1.3865). The FOMC is widely forecast to deliver a rate rise of 0.5 basis points to 1% from its current 0.5%. To curb red-hot inflation, the US central bank is expected to raise interest rates aggressively in the coming months. The benchmark US 10-year bond yield rebounded 11 basis points to 2.93% (2.82% Friday). Other global bond yields were also higher but not to the extent of their US counterpart. Germany’s 10-year Bund rate settled at 0.94% (0.90%). Australia’s 10-year Treasury yield rose to 3.12% (3.08%).
Wall Street stocks tumbled as risk sentiment soured on Friday. The DOW tumbled 2.45% to 33,045 (33,870) while the S&P 500 lost 2.96% to 4,140 from 4,267 Friday.
Data released on Friday saw Australia’s Private Sector Credit ease to 0.4%, against forecasts at 0.6%. Germany’s Import Prices rose to 5.7%, beating estimates for a rise of 3.5% and a previous 1.3%. UK Nationwide House Price Index slumped to 0.3% from 1.1%, and median expectations at 0.8%. US Personal Income in March rose to 0.5%, matching the rise in February but higher than estimates at 0.4%. US Personal Spending (March) climbed to 1.1%, higher than expectations at 0.7%. The US Chicago PMI slumped to 56.4, from 62.9, missing estimates at 62.1. The US University of Michigan Consumer Sentiment dipped to 65.2 from 65.7, and lower than expectations at 65.8.
- EUR/USD – The Euro slumped to an overnight low at 1.0502 before soaring to 1.0593 highs on Friday as shorts scrambled to cover. The shared currency then eased after a choppy session on Friday to close at 1.0545 in late New York.
- USD/JPY – The Japanese currency rebounded against the US Dollar on the risk-off stance amidst positions squaring and adjustments. USD/JPY closed at 129.85 from Friday’s open at 130.85. In volatile trade, the overnight low dealt was at 109.32 while the high was at 103.85.
- GBP/USD – Sterling soared against the Greenback to finish at 1.2575 from its opening at 1.2462. Like the other major FX pairs, the British Pound saw speculative short bets squeezed on month-end position adjustments. Overnight, Sterling slumped to 1.2465 lows before rallying.
- AUD/USD – Despite an initial rally, the Aussie Dollar finished lower against the Greenback as commodity prices eased. On Friday, the AUD/USD pair closed at 0.7060 from 0.7098. Overnight, the Aussie Battler soared to a high at 0.7180 before tumbling lower. Commodity prices retreated after Brent Crude Oil slid 1.1% to USD 106.07 (USD 107.40).
On the Lookout: Ahead of a big week in terms of economic data releases and central bank events, we can expect further volatility. Today should see some consolidation after Friday’s choppy sessions dominated by month-end position adjustments. Today sees the release of global Manufacturing PMIs. Tuesday, (3 May) Australia’s RBA is expected to hike its Overnight Cash Rate to 0.25% from 0.10%. Traders will be looking at the RBA Rate Statement following the meeting. New Zealand releases its Employment data on Wednesday (4 May). Early Thursday (5 May), the US Federal Reserve is widely expected to raise its key rate by 0.50% to 1.0% (0.5%) and begin shrinking its USD 9 trillion balance sheet. The Bank of England meets later the same day with the MPC widely forecast to raise its Official Cash Rate to 1.0% from its current 0.75%. Finally, Friday (6 May) sees the release of US and Canadian Employment reports. It’s one of those “let’s get ready to rumble” weeks!
Trading Perspective: Expect more position adjustments this week heading into one of the busiest weeks in FX. Liquidity will also be at a premium in Asian trade as both China celebrates its Labour Day holidays. Tomorrow Japan markets are closed for their Constitution Day holiday. After trading to fresh 19-year highs, expect the DXY to consolidate further with more adjustments weighing. This enabled the Euro, British Pound, and Japanese Yen to rebound against the Greenback. Expect more of that today with conditions remaining choppy. Traders will be scrutinizing various central bank official’s statements in and around their meetings. After gaining nearly 5% in the month of April alone, the risk is for further easing in the US Dollar amidst volatile conditions.
EUR/USD – The shared currency managed to rebound off the 1.0500 level to close at 1.0545. For today, we can expect immediate support at 1.0525 followed by 1.0500. A break of 1.0500 could open the way lower to 1.0470 strong support (Wednesday’s low). On the topside, immediate resistance is found at 1.0590 (overnight high 1.0593). The next resistance level is found at 1.0620. Look for more volatile trade in a likely range today of 1.0510-1.0610. Prefer to buy dips today, the specs are still short.
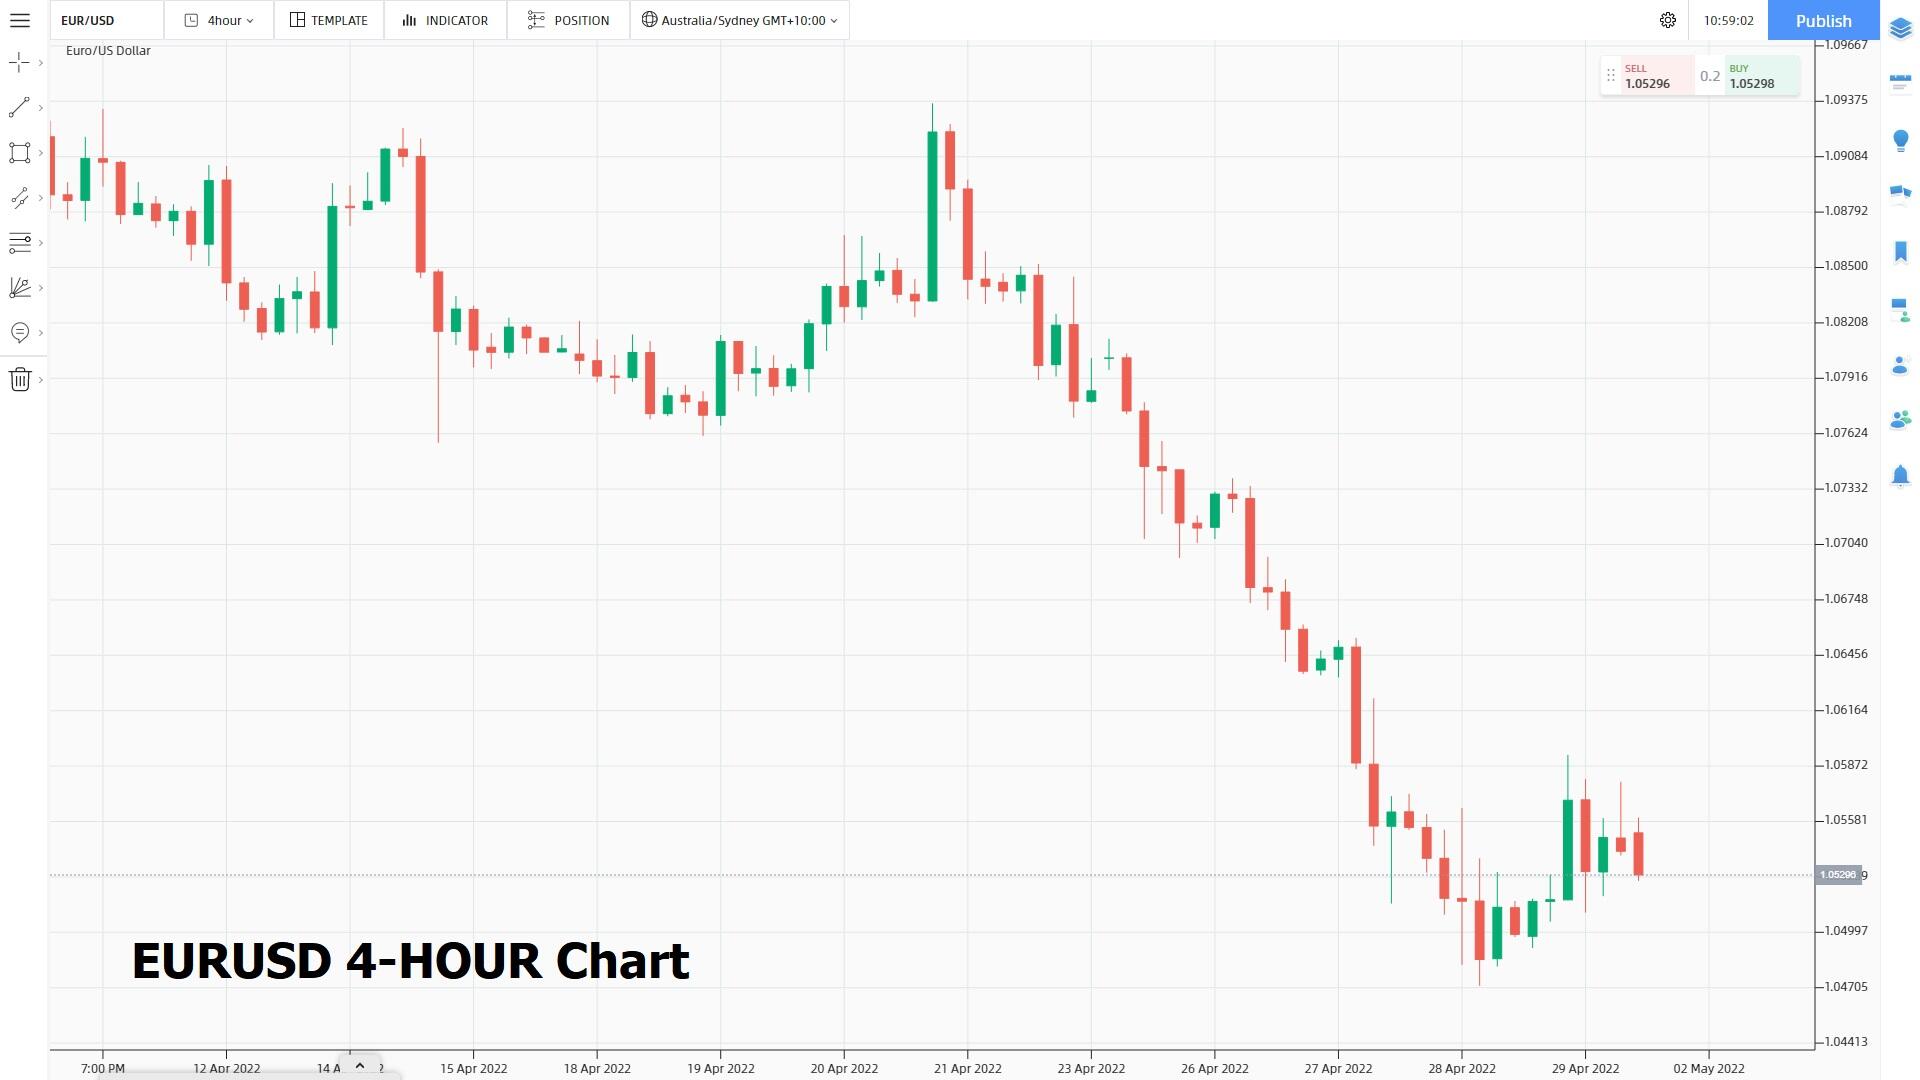
(Source: Finlogix.com)
- USD/JPY – Following a few days of strong gains, the Greenback retreated against the Japanese Yen despite higher US bond yields. A souring of risk sentiment saw demand return for the Japanese currency. In choppy trade, the USD/JPY hit a high at 130.82 before tumbling at the close to 129.85. For today, expect immediate resistance at 130.10, 130.40 and 130.70. Immediate support is found at 129.50 followed by 129.30 and then 129.00. Markets haven’t seen action in this currency pair for quite some time, but things can change quickly in FX. Expect further choppy trade in a likely range today of 129.40-130.40 first up. Preference is to sell rallies.
- AUD/USD – After an initial spike to its overnight high at 0.7180 from Friday’s opening at 0.7098, the Aussie Battler slumped to a low at 0.7053 before recovering mildly to 0.7060. A fall in commodity prices which had previously supported the AUD/USD pair weighed on the antipodean currency. Like the rest of FX, trading was choppy. On the day, immediate support lies at 0.7050 followed by 0.7020 and then 0.7000. Immediate resistance can be found at 0.7090, 0.7120 and 0.7150. Expect a test of 0.7000 at some stage but ahead of a big week, expect that to hold, at least for today. Likely range today 0.7010-0.7130. Just trade the range shag on this puppy today.
- GBP/USD – Sterling rebounded 0.71% against the Greenback to close at 1.2575 in New York on Friday from its opening of 1.2462. Traders are awaiting the Bank of England to raise rates a further 25 basis points to 1.0%. This follows its March hike to 0.75% from a previous 0.50%. On the day, immediate resistance lies at 1.2600 followed by 1.2620 (overnight high traded was 1.2615). Immediate support can be found at 1.2540, 1.2510 and 1.2480. Look for further choppy trade in a likely range today of 1.2485-1.2605. Prefer to sell rallies.
Let’s get ready to rumble for another busy, riveting week in FX. Have a good Monday start and top week ahead all.
Author

Michael Moran
ACY Securities
Michael has over 40 years’ FX experience, including running FX trading desks for some of the largest banks in the world.
















